Fixed vs Floating vs Hybrid Interest Rate: Which One Is Actually Best for Your Loan?
Lakshay Khanna·20 October 2026
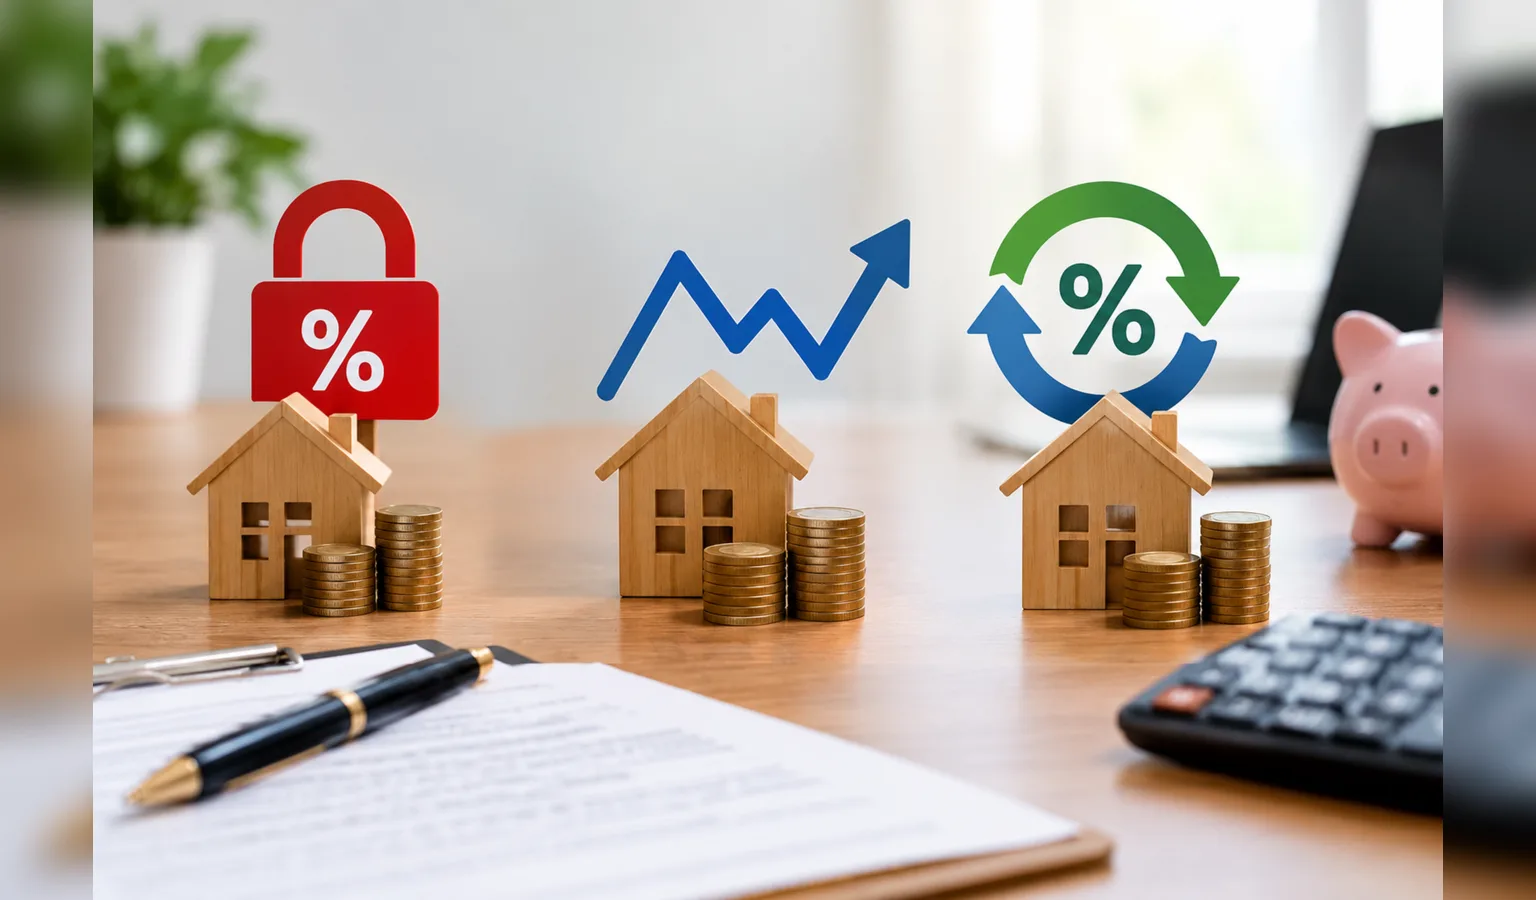
On 7 October the RBI raised the repo rate by 25 basis points, to 5.50%. It was the first hike since February 2023, and within a day my phone had three versions of the same question from relatives. Ab loan mehnge honge kya?
The honest answer: it depends on what kind of interest rate your loan is on. Some people's EMI will go up. Some people won't feel a thing. A few will be paying more without realising it, because their tenure got quietly extended.
Most borrowers never look at this line in their sanction letter. So here are the four types, in plain language, with real numbers.
Not sure what rate you're actually on?
A Credifin loan officer will read your sanction letter with you and tell you what this hike changes. Across 14 states, and the call is free.
Check your eligibility →The four types of interest rates in India
1. Fixed interest rate
The rate is locked when you sign. If it's 11%, it stays 11% until the last EMI, whatever the RBI does.
That's the whole appeal. Your EMI is the same in month 3 and month 53, so you can budget around it. The repo hike this month means nothing to a fixed-rate borrower.
The catch is that lenders charge for this certainty. A fixed rate usually sits 1 to 2.5 percentage points above the floating rate on the same product at the time you borrow. When rates fall later, which they did right through 2025, you don't benefit at all. And fixed-rate loans often carry a foreclosure charge of 2% to 4% if you want to close early.
In India, truly fixed rates are common on car loans, two-wheeler loans, e-rickshaw loans and personal loans. These are short loans of 1 to 5 years, so the lender can price the risk easily. On a 20-year home loan, a genuinely fixed rate is rare, and when someone offers one, read the fine print. Many "fixed" home loans are fixed only for the first few years.
2. Floating interest rate
The rate moves with a benchmark. For most bank home loans that benchmark is the repo rate itself, through what's called EBLR (external benchmark lending rate). Your rate equals repo plus a spread the bank fixes for you on day one.
Say your spread is 3%. With repo at 5.25% you paid 8.25%. Now repo is 5.50%, so you'll pay 8.50% from your next reset date. Banks have to reset EBLR loans at least once every three months, so some borrowers will see the change by January.
NBFCs work a bit differently. Most link their floating loans to their own internal benchmark, not directly to the repo, so changes come slower and aren't always the same size. Your loan agreement will name the benchmark. Look for it.
Here's what the hike looks like on an actual loan. Take a ₹30 lakh home loan over 20 years:
₹30 lakh home loan, 20 years
| Rate | EMI | Change |
|---|---|---|
| 8.50% | about ₹26,035 | |
| 8.75% | about ₹26,510 | +₹475 a month |
₹475 a month doesn't sound like much. Over 20 years it adds up to around ₹1.1 lakh. And a lot of banks won't touch your EMI at all. They'll extend your tenure by a few months instead, which feels painless now and costs more in the end.
My suggestion: when your bank sends the reset letter, ask them to raise the EMI instead of extending the tenure. Since 2023 the RBI has required lenders to give you that choice at reset, along with an option to switch to a fixed rate. Most people never ask, so they never hear about it.
The case for floating is still strong. It starts cheaper, there's no prepayment penalty for individual borrowers, and when rates drop you benefit automatically. Over a 15 to 20 year home loan, rates usually go up and come down a few times. Floating borrowers have generally come out ahead in India over long stretches, though nobody can promise that for the next cycle.
3. Hybrid (or mixed) rate
This one is fixed for the first few years, usually 2, 3 or 5, and floating after that.
Banks and housing finance companies sell it as the best of both. You get a predictable EMI in the early years, which is usually when money is tightest because you've just paid the down payment, registry and furnishing costs. Then the loan moves to floating for the long remainder.
It's a reasonable product, but price it carefully. The fixed portion is generally priced higher than plain floating. If rates stay flat or fall during those first years, you've paid extra for insurance you didn't use. Also check what spread you'll get when it switches to floating. Some lenders set that spread a little higher than what a fresh floating borrower would get.
I'd consider hybrid if you're stretched in the first few years and expect your income to grow, for example a young salaried couple or someone just starting a business.
4. Flat rate vs reducing balance rate
This one isn't really a fourth type of rate. It's a different way of calculating the interest, and it catches people more than anything above.
With a reducing balance rate, interest is charged only on what you still owe. As you pay down the principal, the interest portion of each EMI shrinks. Home loans, LAP and most bank loans work this way.
With a flat rate, interest is charged on the full original amount for the whole tenure, even though you're repaying some of it every month. You still see flat rates on some consumer durable finance, small vehicle loans and loans from local finance shops.
Here's why it matters. Take ₹1 lakh over 2 years at a "12% flat" rate:
Interest = ₹1,00,000 × 12% × 2 = ₹24,000
EMI = ₹1,24,000 ÷ 24 = about ₹5,167
The same EMI on a reducing balance basis works out to roughly 21.6%. So "12% flat" sounds cheap and costs almost double.
If a dealer or lender quotes you a rate, ask one question: flat ya reducing? If they say flat, roughly double it in your head to compare. Better still, ask for the APR, since every regulated lender now has to show it in the Key Fact Statement before you sign.
So, ghar ke liye loan konsa best hai?
For most people buying a home in 2026, I'd still pick floating. Here's why:
Fixed makes more sense if your budget has no room at all, if you're near retirement and want certainty, or if the loan is short anyway. Hybrid sits in the middle, for people who need breathing room in the early years.
For a car, two-wheeler or e-rickshaw loan, the question mostly answers itself. These are short loans, they're mostly fixed by default, and a 25 bps repo move barely touches them.
If you're also deciding how much to borrow, our home loan down payment guide shows why putting in a little more upfront saves more interest than chasing a slightly lower rate. And if you're still choosing between pledging an asset or not, we've compared secured and unsecured loans separately.
What to check in your loan agreement today
Pull out your sanction letter and look for four things:
Ten minutes of reading tells you whether this repo hike changes anything for you, and how much.
FAQs
Will my EMI go up after the October 2026 repo hike?
If your loan is floating and linked to the repo (most bank home loans since 2019), your rate will rise by 0.25% at the next reset, within three months. Fixed-rate loans don't change. NBFC floating loans may change later, depending on their internal benchmark.
Can I switch from floating to fixed now?
Yes. At reset, lenders must offer you the option to switch to a fixed rate, usually for a fee. Do the math first, though. The fixed rate offered today will probably be 1 to 2 points above your current floating rate.
Is a fixed rate home loan a good idea in 2026?
Only if certainty matters more to you than cost. With repo at 5.50%, locking in a rate 1.5 points higher for 20 years is a big premium to pay for protection against a few possible hikes.
What is the difference between flat and reducing interest rate?
A flat rate charges interest on the full original loan amount for the whole tenure. A reducing rate charges interest only on what you still owe. The same number on a flat basis costs roughly 1.7 to 1.9 times more.
Does an NBFC follow the repo rate like banks do?
Not directly. Most NBFCs use their own benchmark rate, so repo changes reach their borrowers more slowly and not always in full. Check the benchmark clause in your agreement.
Which loans are usually fixed rate in India?
Personal loans, car loans, two-wheeler loans and most vehicle loans from NBFCs. Home loans and loans against property are mostly floating.
Talk to someone before you lock in
Whether you're taking a new home loan or loan against property, or just trying to figure out what this hike means for your existing EMI, a Credifin loan officer can walk you through your numbers. We're in 14 states, and a phone call is free.
Ready when you are
Home loans, loans against property and vehicle finance across 14 states, assessed on your real numbers.
Check your eligibility →Talk to Credifin
Credifin is an RBI-registered NBFC lending across 14 states and 200+ locations. CRISIL BBB- / Stable.
079651-74500 | info@credif.in
Find your nearest branch →
Credifin Limited is an RBI-registered NBFC, CRISIL BBB-/Stable. Loans at the sole discretion of the company. EMI figures are approximate and for illustration only.
This might catch your interest