RBI-Registered NBFC · CRISIL BBB– / Stable · Listed on MSE · Lending since 1992

Drive Your Ambitions: Tailored Two-Wheeler Loans for a Smoother Journey

Experience hassle-free rides with our customized two-wheeler loans designed to accelerate your dreams and ensure a seamless journey ahead.
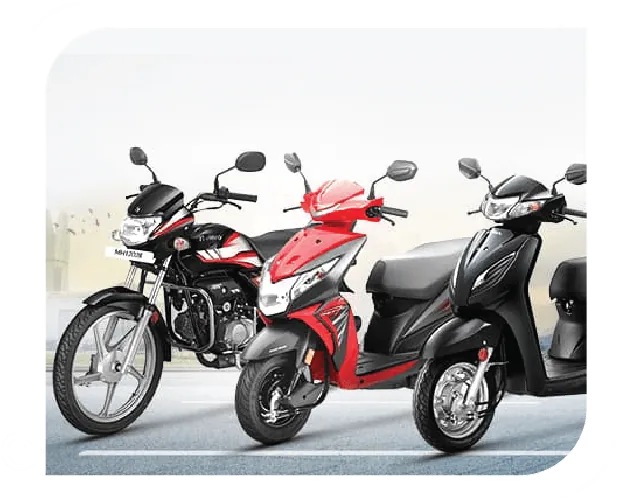
New Two-Wheeler Loan

Features and Benefits

Experience the freedom of the open road with our two-wheeler loan, offering competitive interest rates, flexible repayment options, and quick approval process

Insurance

Insurance

We safeguard your investment by providing financial coverage for accidents, & natural calamities, ensuring that replacement costs are taken care of

Up to 100% financing

Up to 100% financing

Our up to 100% financing options ensure that you can leave no compromise behind when it comes to choosing your dream two-wheeler

Quick approvals and disbursals

Quick approvals and disbursals

We often provide quick loan approval and disbursal, ensuring you can get your two-wheeler without unnecessary delays

Minimal documentations

Minimal documentations

We simplify the documentation process compared to other types of loans, making it easier

Customized Loan

Customized Loan

Flexibility to choose loan amount, repayment tenure, and loan type based on your preferences

Our Presence

Our Presence

We are available in 14 States, 33+ Regional Offices, 200+ Locations, and with 750+ Team Strength

Calculate Your EMI

Plan your finances better with our easy-to-use EMI calculator.

  • Instant Calculation

    See results as you adjust

  • Clear Breakdown

    Principal vs Interest

  • Mobile Friendly

    Works anywhere

EMI Calculator

₹
₹1 Lakh₹1 Crore
%
8%26%
Years
1 Year30 Years

Your Monthly EMI

₹1,243.52
Principal Amount₹1,00,000
Total Interest₹1,98,444.99
Total Payable₹2,98,444.99
Tenure20 Years (240 months)
a quick and transparent process

We have a simple online application

  1. Check Eligibility

    Check Eligibility

    Check eligibility criteria before applying for a loan to ensure approval possibilities.

  2. Calculate Your EMI

    Calculate Your EMI

    Estimate your monthly EMI effortlessly with our user-friendly loan calculator.

  3. Check Required Documents

    Check Required Documents

    Ensure which necessary documents are required for loan application.

  4. Fill Application Form

    Fill Application Form

    Accurately provide all required information in the loan application form for prompt processing.

Eligibility and Documents

Essential documents that need to be provided to complete the process successfully are listed below:

  1. Identification & Address Proof

    Any government-issued identification document such as Aadhaar card, PAN card, passport, voter ID card, or driving license.

  2. Income Proof

    To assess the applicant’s repayment capacity, income proof is required. It can include salary slips, bank statements, income tax returns (ITR), or a letter from the employer.

  3. Bank statements

    The last 3 to 6 months of bank statements are required to evaluate the applicant’s financial stability.

  4. Passport-Size Photos

    Recent photographs of the loan applicant.

  5. Employment Proof

    If the applicant is salaried, they may need to provide an employment certificate from their employer. If self-employed, relevant business documents like business registration, GST certificate, etc., may be required.
Frequently Asked Questions

Questions From Customers

Customer care representative
What is a two-wheeler loan?

A two-wheeler loan provides a convenient way for individuals to purchase a motorcycle or scooter without having to pay the entire amount upfront, making it more affordable and manageable through structured monthly payments.

Who is eligible for a two-wheeler loan?

Eligibility criteria typically include age (usually 18-65 years), income stability, employment status, and credit score. Self-employed individuals may need to provide additional documentation compared to salaried individuals.

What are the benefits of using a two-wheeler loan?
  • Lower Upfront Costs: Spread the cost over time, making it more affordable.
  • Immediate Ownership: Get your two-wheeler right away without waiting to save the full amount.
  • Flexible Repayment: Choose repayment terms that fit your budget with manageable EMIs.
  • Financial Flexibility: Preserve savings for emergencies and maintain better cash flow.
  • Credit Score Improvement: Build or improve your credit history with timely repayments.
What documents do I need to apply for a two-wheeler loan?
  • Identity Proof: Aadhaar card, passport, voter ID, or driving license.
  • Address Proof: Utility bills, rental agreement, or passport.
  • Income Proof: Salary slips, bank statements, or income tax returns.
  • Photographs: Passport-sized photos.
  • Age Proof: Birth certificate, PAN card, or school leaving certificate.
What is the minimum credit score required for a two-wheeler loan?

The minimum credit score required for a two-wheeler loan typically ranges from 600 to 650. However, requirements can vary by lender, with some offering loans to those with lower scores but possibly at higher interest rates.

Can I get a two-wheeler loan if I am self-employed?

Yes, you can get a two-wheeler loan if you are self-employed.

How long does it take to get a two-wheeler loan approved?

Approval for a two-wheeler loan typically takes between 24 hours to a few days, depending on the lender and the completeness of your documentation. Some lenders offer instant or same-day approval for online applications with minimal documentation.

What is the maximum loan amount I can get for a two-wheeler loan?

The maximum loan amount for a two-wheeler loan typically depends on several factors, including the lender's policies, the cost of the two-wheeler, and your income and credit profile. Generally, lenders offer up to 85% to 100% of the on-road price of the two-wheeler. Some lenders may have a specific upper limit, which can range from ₹50,000 to ₹1.5 lakhs or more.

What are the typical loan terms for a two-wheeler loan?
  • Loan Tenure: 12 to 48 months (1 to 4 years), with some lenders offering up to 60 months.
  • Interest Rates: Generally range from 8% to 20% per annum, depending on the lender, your credit score, and income.
  • Loan Amount: Up to 85% to 100% of the on-road price of the two-wheeler.
  • Repayment Options: Monthly EMIs (Equated Monthly Installments).
  • The interest rate on a two-wheeler loan can vary widely depending on several factors, including Lender: Different banks and financial institutions offer different interest rates.
  • Credit Score: A higher credit score usually results in a lower interest rate.
  • Loan Amount: The amount borrowed can influence the interest rate.
  • Loan Tenure: The length of the loan term can impact the interest rate, with longer tenures sometimes having higher rates.
  • Promotional Offers: Banks and lenders might have promotional rates or special offers at certain times.
Can I make a down payment on the two-wheeler?

Yes, typically you can make a down payment on a two-wheeler purchase. Down payments are common in vehicle purchases and can help reduce the amount you need to finance through a loan, which can in turn lower your monthly payments or shorten the loan term.

What are the different repayment options for a two-wheeler loan?
  • Equal Monthly Installments (EMIs): This is the most common method where you pay a fixed amount each month, which includes both principal and interest, over a specified period.
  • Balloon Payment: A lump sum payment at the end of the loan term, which can be lower than regular EMIs but requires you to pay a larger amount at once.
  • Step-Up/Step-Down EMIs: EMIs that increase or decrease over time. Step-up EMIs start lower and increase gradually, while step-down EMIs start higher and decrease gradually.
  • Flexible EMIs: Some lenders offer flexibility in EMI payments, allowing you to increase or decrease your monthly payments based on your financial situation.
  • To avoid these issues, it's crucial to communicate with your lender if you anticipate difficulty making a payment. Some lenders may offer options such as restructuring the loan or temporarily adjusting payments to help you avoid defaulting. It's important to read and understand your loan agreement thoroughly and prioritize making payments on time to maintain your financial health.
What happens if I miss a two-wheeler loan payment?
  • Late Payment Fees: Lenders typically charge a late fee if you miss a payment. This fee varies depending on the lender and the terms of your loan agreement.
  • Negative Impact on Credit Score: Missing payments can negatively impact your credit score. This can make it harder to get approved for loans or credit cards in the future, or you may receive less favorable terms.
  • Accumulation of Interest: Interest continues to accrue on the unpaid amount, which means you'll end up paying more overall.
  • Legal Action: In extreme cases of repeated missed payments, the lender may take legal action to recover the amount owed. This could lead to repossession of the two-wheeler or other legal consequences.
  • Bullet EMIs: Interest is paid monthly, and the principal amount is paid at the end of the term.
What other fees are associated with a two-wheeler loan?
  • Processing Fee: Charged by the lender for processing your loan application.
  • Documentation Charges: Fees for preparing loan documents.
  • Late Payment Fee: Charged if you fail to make your EMI payment on time.
  • Prepayment Charges: Some lenders may charge a fee if you decide to pay off your loan before the end of the loan term.
  • Loan Insurance: Optional insurance to cover loan repayments in case of unforeseen events like disability, death, or loss of job.
  • GST (Goods and Services Tax): Applicable taxes on the loan amount or fees charged.
  • These fees can vary depending on the lender and the terms of your loan agreement. It's essential to carefully review all associated fees and charges before signing the loan agreement to understand the total cost of borrowing.
Can I finance a used two-wheeler with a loan?

Yes, you can finance a used two-wheeler with a loan. Many banks, financial institutions, and even some two-wheeler dealerships offer loans specifically for purchasing used vehicles.

What type of two-wheeler can I finance with a loan?
  • Motorcycles: Both commuter motorcycles and premium motorcycles can be financed.
  • Scooters: Including traditional scooters and maxi-scooters.
  • Mopeds: Small, lightweight motorized bicycles.
  • Electric Two-Wheelers: Electric scooters, motorcycles, or bicycles.
  • Sports Bikes: High-performance motorcycles designed for sport riding.
  • Cruisers: Motorcycles designed for comfortable long-distance riding.
  • The specific types of two-wheelers you can finance may vary depending on the lender's policies and loan offerings. It's essential to check with the lender or financing institution to confirm which types of two-wheelers are eligible for financing under their loan programs.
Are there any special two-wheeler loan schemes for women?

Yes, several banks and financial institutions offer special two-wheeler loan schemes designed specifically for women. These schemes often come with certain benefits and features tailored to meet the needs of female customers. These schemes aim to empower women by making it easier and more affordable for them to finance a two-wheeler purchase. It's advisable for women considering a two-wheeler loan to inquire with various lenders about any special schemes they offer and compare them with standard loan options to find the most beneficial terms.

Can I finance additional accessories for my two-wheeler with the loan?

Yes, you can often finance additional accessories for your two-wheeler with the loan. Many lenders provide options to include the cost of accessories in the overall loan amount. Before deciding to finance accessories, compare the interest rates and terms offered by different lenders to ensure you are getting the most competitive deal. Additionally, consider whether it's more cost-effective to purchase accessories separately or include them in the loan.

Does the loan cover registration and other one-time fees for the two-wheeler?

Yes, when you apply for a two-wheeler loan, the total loan amount can include these one-time fees along with the cost of the vehicle itself. This helps simplify the purchasing process by bundling all expenses into a single loan package. It's important to check with your lender to confirm which specific fees are covered by the loan and to understand any additional charges or requirements that may apply.

Can I sell my used two-wheeler before the loan is fully repaid?

Yes, several banks and financial institutions offer special two-wheeler loan schemes designed specifically for women. These schemes often come with certain benefits and features tailored to meet the needs of female customers. These schemes aim to empower women by making it easier and more affordable for them to finance a two-wheeler purchase. It's advisable for women considering a two-wheeler loan to inquire with various lenders about any special schemes they offer and compare them with standard loan options to find the most beneficial terms.

Can I finance additional accessories for my two-wheeler with the loan?

Yes, you can often finance additional accessories for your two-wheeler with the loan. Many lenders provide options to include the cost of accessories in the overall loan amount. Before deciding to finance accessories, compare the interest rates and terms offered by different lenders to ensure you are getting the most competitive deal. Additionally, consider whether it's more cost-effective to purchase accessories separately or include them in the loan.

Does the loan cover registration and other one-time fees for the two-wheeler?
  • Yes, typically a two-wheeler loan can cover registration and other one-time fees associated with purchasing the vehicle
  • Registration Charges: Fees paid to the Regional Transport Office (RTO) for registering the two-wheeler in your name.
  • Road Tax: Tax paid to the state government for using the vehicle on public roads.
  • Insurance Premium: The first year's insurance premium may be included in the loan amount, depending on the lender's policies.
  • Handling Charges: Charges for processing paperwork and documentation related to the purchase.
  • When you apply for a two-wheeler loan, the total loan amount can include these one-time fees along with the cost of the vehicle itself. This helps simplify the purchasing process by bundling all expenses into a single loan package. It's important to check with your lender to confirm which specific fees are covered by the loan and to understand any additional charges or requirements that may apply.
View MoreView Less