Affordable Ownership
Save money by opting for a used two-wheeler and still benefit from financing
Experience the joy of ownership with seamless processing and unbeatable rates – Your journey begins with hassle-free used two wheeler loans at your fingertips.
Experience the freedom of the open road with our used two-wheeler loan, offering competitive interest rates, flexible repayment options, and a quick approval process
Save money by opting for a used two-wheeler and still benefit from financing
Speedy loan approval means you can own your pre-owned bike sooner
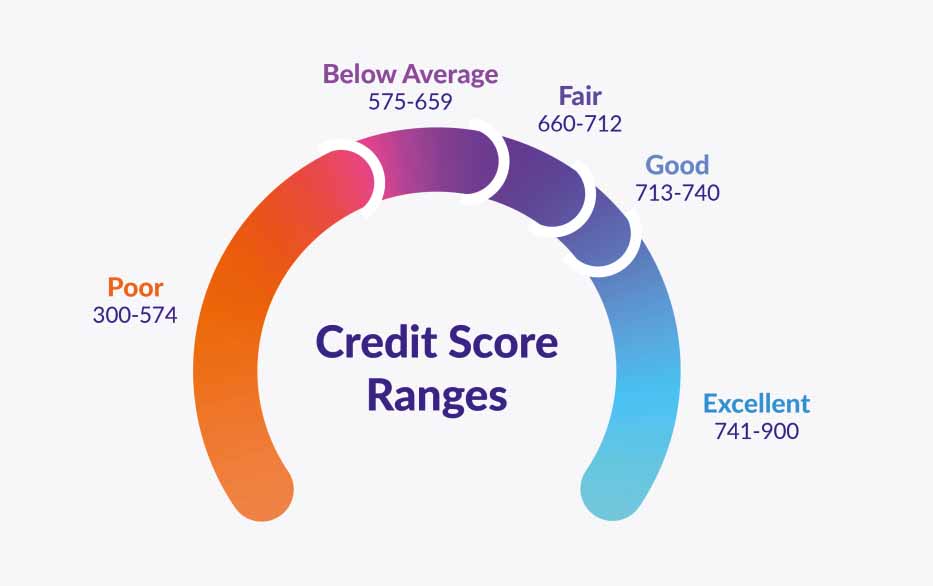
Timely repayments positively impact your credit score
Enjoy the flexibility of choosing an EMI that aligns with your budget
Purchase your dream bike without the need for a lump sum payment
Secure your ownership with a legitimate and straightforward financing process
Plan your finances better with our easy-to-use EMI calculator.
See results as you adjust
Principal vs Interest
Works anywhere
EMI Calculator
Your Monthly EMI
a quick and transparent process
Check eligibility criteria before applying for a loan to ensure approval possibilities.
Estimate your monthly EMI effortlessly with our user-friendly loan calculator.
Ensure which necessary documents are required for loan application.
Accurately provide all required information in the loan application form for prompt processing.
Essential documents that need to be provided to complete the process successfully are listed below:
Any government-issued identification document such as Aadhaar card, PAN card, passport, voter ID card, or driving license.
To assess the applicant’s repayment capacity, income proof is required. It can include salary slips, bank statements, income tax returns (ITR), or a letter from the employer.
The last 3 to 6 months of bank statements are required to evaluate the applicant’s financial stability.
Recent photographs of the loan applicant.
If the applicant is salaried, they may need to provide an employment certificate from their employer. If self-employed, relevant business documents like business registration, GST certificate, etc., may be required.
Frequently Asked Questions
A used two-wheeler loan is a type of financing provided by banks or financial institutions to individuals for purchasing a pre-owned motorcycle or scooter. This loan typically covers a significant portion of the vehicle's cost, allowing the buyer to repay the amount in installments over a specified period. Key features often include competitive interest rates, flexible repayment terms, and eligibility criteria based on the borrower's creditworthiness and income.
Yes, the minimum credit score requirement can be higher for used two-wheeler loans compared to new two-wheeler loans. Lenders often see used vehicle loans as riskier, so they may set a higher credit score threshold to ensure the borrower has a good credit history and repayment capability. However, the exact requirement can vary by lender.
Yes, you can get a used two-wheeler loan if you are self-employed. You will need to provide proof of a stable income, such as recent bank statements, income tax returns, and other relevant financial documents to demonstrate your ability to repay the loan.
The approval time for a used two-wheeler loan can vary, but it typically takes between a few hours to a few days. This depends on the lender's processes, the completeness of your application, and the verification of your documents. Some lenders offer instant approvals if all criteria are met and documents are in order.
The maximum loan amount for a used two-wheeler loan typically depends on factors such as the lender's policies, the value of the vehicle, and the borrower's eligibility. Generally, lenders offer up to 70-85% of the vehicle's current market value. Some lenders might have a cap on the maximum loan amount, often ranging from ₹50,000 to ₹1,00,000, but this can vary widely.
The interest rate on a used two-wheeler loan typically ranges from 10% to 20% per annum. The exact rate depends on factors such as the lender's policies, the borrower's credit score, income, and overall financial profile.
Yes, you can make a down payment on a used two-wheeler. The down payment typically covers the portion of the vehicle's cost that the loan does not, often ranging from 15% to 30% of the vehicle's market value. The exact amount can vary depending on the lender's policies and the loan terms.
Yes, it's generally a good idea to consider getting a warranty for a used two-wheeler, especially if you're financing it with a loan.
Prepayment charges on used two-wheeler loans vary by lender and the terms of the loan agreement. Some lenders may impose prepayment penalties if you choose to repay the loan amount before the scheduled tenure ends. These charges are typically designed to compensate the lender for the interest income they would have earned if you had continued with the loan as per the original schedule.
Yes, two-wheeler insurance is mandatory for a used two-wheeler loan. Lenders typically require borrowers to have comprehensive insurance coverage for the vehicle throughout the loan tenure. This insurance helps protect the lender's financial interest in the vehicle in case of damage or loss. The insurance premium is an additional cost that the borrower needs to bear along with the loan repayment. It covers damages to the vehicle due to accidents, natural calamities, theft, and third-party liabilities. Before finalizing the loan, the lender will usually require proof of insurance coverage for the two-wheeler. It's important to factor in the cost of insurance when budgeting for the total cost of financing a used two-wheeler.
Using a loan broker for a used two-wheeler loan can be beneficial if you value convenience, access to multiple lenders, and expert advice. However, it's essential to carefully consider the costs and ensure transparency in the broker's services and fees. If you're comfortable researching and negotiating on your own, exploring direct options with lenders could also be a viable approach to find a competitive loan deal.
LET'S CONNECT