Will Your Loan Interest Rate Change After the RBI Repo Rate Hike?
Lakshay Khanna·13 October 2026
Short answer: only if your loan is on a floating rate. Fixed-rate loans don't change at all. Floating bank loans linked to the repo will go up by about 0.25% at your next reset. NBFC floating loans may or may not follow, and usually later.
Since the RBI raised the repo rate to 5.50% on 7 October, the question I keep hearing is some version of meri EMI badhegi kya? It's a fair question, and the honest answer is different for almost every type of loan. So I've gone through them one by one.
If you want the background on the hike itself, I've covered that separately in what the October 2026 repo hike means.
Home loan from a bank (floating)
This is the one that moves.
Most home loans sanctioned by banks since October 2019 are linked to an external benchmark, which in practice means the repo rate. Your rate is the repo plus a fixed spread. Repo went up 0.25%, so your rate goes up 0.25%.
When? At your next reset date. Banks have to reset these loans at least once every three months, so you'll see it by January at the latest.
Here's what that looks like on a ₹50 lakh loan over 20 years:
₹50 lakh home loan, 20 years
| EMI | Tenure | |
|---|---|---|
| Before, at 8.50% | about ₹43,390 | 240 months |
| Option A: EMI goes up, at 8.75% | about ₹44,180 | 240 months |
| Option B: EMI stays, tenure stretches | ₹43,390 | about 252 months |
Option B looks painless, and it's what a lot of banks do by default. But you end up paying for about a year longer. Over the full loan that costs roughly ₹3.5 lakh more than option A. Ask your bank for option A. Since 2023 the RBI has required lenders to give you that choice at reset.
If your home loan is older and still on MCLR, it'll move too, but more slowly. MCLR responds to the bank's own funding costs, and it usually resets once a year on your loan.
Home loan or LAP from an NBFC or housing finance company
These usually don't track the repo directly. Most NBFCs price floating loans off their own benchmark rate, which reflects what it costs them to borrow from banks and markets.
Here's how it tends to play out. When the repo goes up, banks charge NBFCs a bit more. Over the next few months, the NBFC may raise its benchmark, and your rate follows. Sometimes the increase is smaller than 0.25%. Sometimes it's skipped if the NBFC's own costs haven't changed much.
Your loan agreement names the benchmark and how often it can reset. That's the clause to read. If it says the rate is fixed, as many NBFC vehicle and small business loans are, nothing changes.
Not sure which clause to look for?
Bring your sanction letter to a Credifin loan officer and we'll find it with you. Across 14 states, and the call is free.
Check your eligibility →Car loan and two-wheeler loan
Almost always fixed. Your EMI stays exactly the same until the last payment.
New car and bike loans may get slightly more expensive over the coming weeks, as lenders update their rate cards. On a ₹6 lakh car loan over 5 years, a 0.25% bump works out to roughly ₹70 to ₹75 more a month. Not something to change your plans over.
The same goes for e-rickshaw loans and EV two-wheeler loans. These are short, fixed loans, and the repo barely touches them.
Personal loan
Fixed, in the vast majority of cases. Existing EMIs don't change.
Rates on new personal loans depend much more on your credit score, income and the lender than on the repo. A 0.25% repo move is small next to the 5 to 10 point range you see across lenders for the same borrower.
Business loan and MSME loan
This one depends. Bank loans to MSMEs are often linked to an external benchmark like the repo, so they move the same way home loans do. Working capital limits such as cash credit and overdraft usually reprice quickly too.
NBFC business loans are more often fixed, or tied to the lender's own benchmark. Check your sanction letter.
Credit card and pay later
Nothing changes. These carry very high rates already, often 36% to 42% a year if you revolve a balance, and they aren't linked to the repo.
Quick table: does my loan change?
Loan by loan, after the October 2026 repo hike
| Loan type | Usually | Changes after repo hike? |
|---|---|---|
| Bank home loan (since Oct 2019) | Floating, repo-linked | Yes, +0.25% at next reset |
| Older bank home loan | Floating, MCLR | Yes, slower |
| NBFC/HFC home loan or LAP | Floating, own benchmark | Maybe, later |
| Car / bike / e-rickshaw loan | Fixed | No |
| Personal loan | Fixed | No |
| Bank MSME loan | Often repo-linked | Yes |
| NBFC business loan | Often fixed | Usually no |
| Credit card / pay later | Not linked | No |
What you can actually do about it
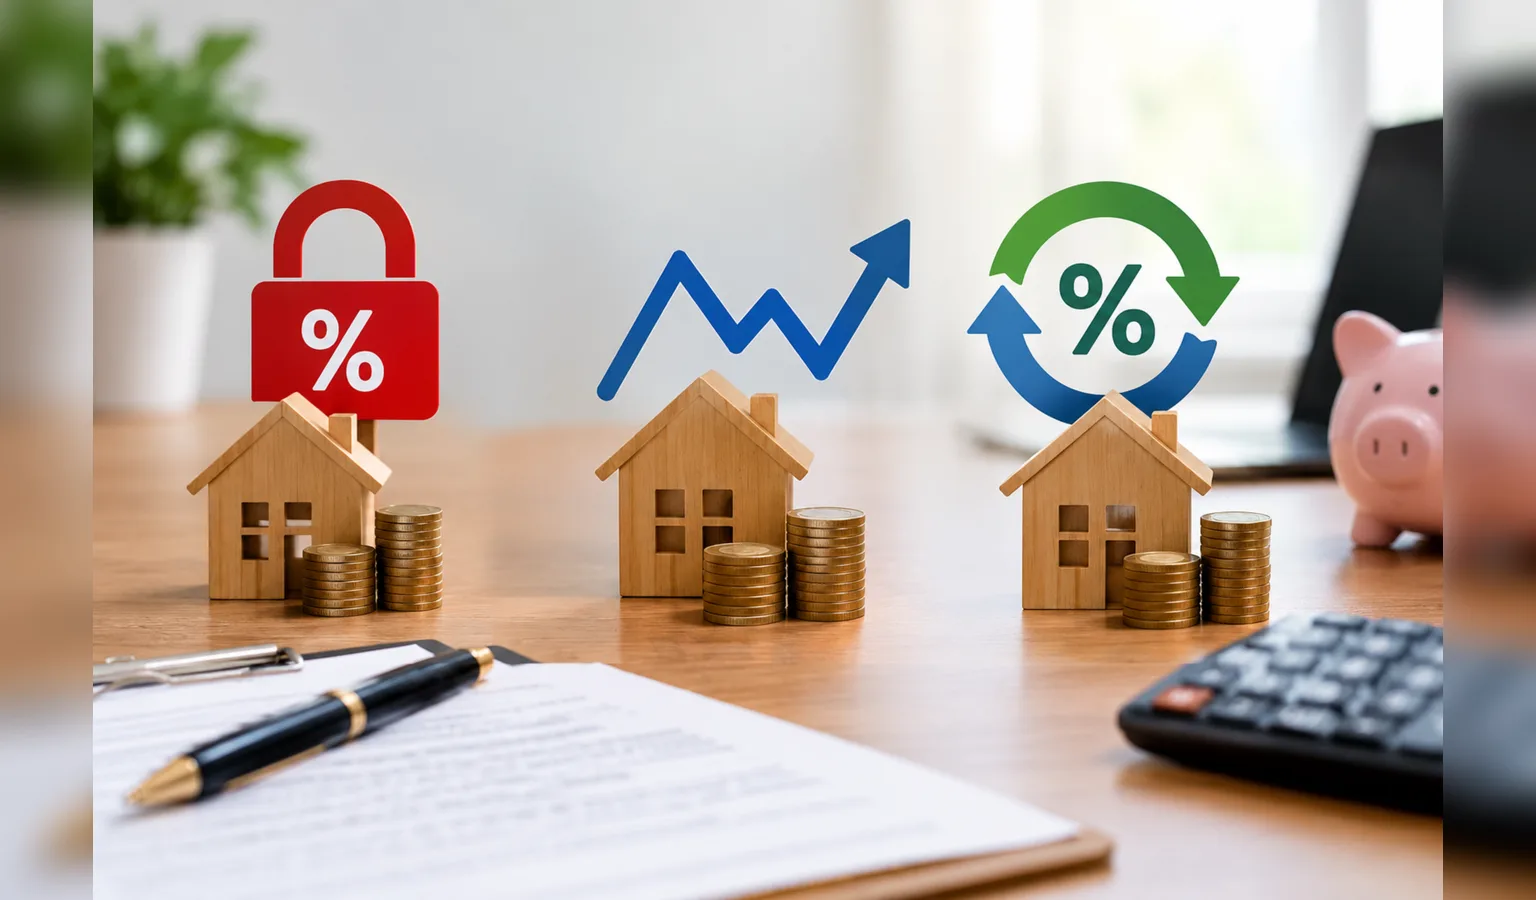
Don't switch to fixed in a panic. At reset your bank has to offer a switch to fixed, but the fixed rate is usually 1 to 2 points higher. Paying that for 20 years to avoid one or two small hikes rarely makes sense. Our explainer on fixed vs floating rates goes into this properly.
Taking a new loan right now?
Don't rush it to beat the December meeting, and don't put off a purchase you need only because of a 0.25% move. Compare loan type, lender, spread and fees. Those make a much bigger difference than the timing.
If you're wondering whether this is the start of a longer run of hikes, that comes down to inflation. I've looked at that in is inflation causing interest rates to rise.
FAQs
Will my home loan EMI increase after the October 2026 repo hike?
If it's a repo-linked floating loan from a bank, yes, by about 0.25% at your next reset, or the bank may extend your tenure instead. Fixed-rate loans don't change.
When will the new rate apply to my loan?
From your next reset date. For repo-linked bank loans that's within three months. MCLR loans usually reset yearly.
Do NBFC loans increase with the repo rate?
Not directly. NBFCs use their own benchmark, so changes, if any, come later and are sometimes smaller.
Will my car loan EMI change?
Almost certainly not. Car loans are usually fixed for the full tenure.
Is it better to extend tenure or increase EMI?
Increasing the EMI. Extending tenure keeps the monthly amount the same but costs noticeably more in total interest.
Want someone to check your loan?
Bring your sanction letter to any Credifin branch across 14 states, or call us. A loan officer will tell you whether this hike affects you, and if you're planning a new home loan or loan against property, what you should expect.
Ready when you are
Home loans, loans against property and vehicle finance across 14 states, assessed on your real numbers.
Check your eligibility →Talk to Credifin
Credifin is an RBI-registered NBFC lending across 14 states and 200+ locations. CRISIL BBB- / Stable.
079651-74500 | info@credif.in
Find your nearest branch →
Credifin Limited is an RBI-registered NBFC, CRISIL BBB-/Stable. Loans at the sole discretion of the company. EMI figures are approximate and for illustration only.
This might catch your interest