Used Two Wheeler Loan in Punjab: Age Limits, Valuation, and the Paperwork That Actually Delays You
Vansh Budhiraja·01 September 2026
Baljit repairs mobile phones from a counter the size of a cupboard in Moga. Screens, batteries, the occasional water job he pretends he can fix.
In March he bought a 2019 Splendor from a man who ran a small used vehicle business out of a gali off the Ferozepur road. Fifty two thousand, agreed over two visits and a cup of tea. Keys handed over the same evening. Baljit rode it home feeling like he had done well, because on price he had.
The RC still carried a finance company's name on it.
The seller knew. He said it was a formality, that the loan had been cleared ages ago, that the NOC would come in a week. It came in eleven weeks, after Baljit had rung him roughly forty times and eventually turned up at his house on a Sunday.
For three months Baljit owned a bike he could not register in his name, could not have properly insured in his name, and could not have sold if he had wanted to.
"Gaadi mil gayi, kaagaz teen mahine baad mile."
I got the bike. The papers came three months later.
Punjab has a big, busy, genuinely useful second hand two wheeler market. Moga, Bathinda, Patiala, Hoshiarpur, every one of them has a lane full of vehicles in decent shape at prices that make sense. Most sellers are fine. The trade works.
What trips people up is almost never the machine. It is the sequence. A used two wheeler loan involves two parties, two sets of documents and an RTO, and if you take those steps in the wrong order you spend months untangling something that a single question at the start would have prevented.
So this is the order.
Buying second hand and want to know what it will value at before you agree a price?
Ask us first. Clean file decided in 3 to 7 working days.
Check your eligibility →What lenders will and will not fund
Before anything else, check that the bike you have fallen for is even financeable. Plenty are not, and people discover this after paying a token amount.
Financeable or not
| Vehicle | Usually funded | Usually declined |
|---|---|---|
| Age at purchase | Up to 5 years, some lenders stretch to 7 | Older than 8 years, or where loan tenure would take it past 10 |
| Kilometres | Under roughly 60,000 for a commuter | Very high running with no service history |
| Registration | Punjab registered, clean RC, single or second owner | Out of state without NOC, or fourth owner and beyond |
| Papers | RC, valid insurance, PUC, chassis matching | Missing RC, active hypothecation, pending challans |
| Condition | Roadworthy, no structural damage | Accident repaired frames, tampered odometer |
| Category | Commuter motorcycles and scooters, mainstream brands | Heavily modified bikes, obscure or discontinued brands |
Indicative. Age and kilometre limits vary between lenders and by how good the individual vehicle looks on inspection.
The age rule catches the most people. A 2017 bike in lovely condition can still be declined simply because a 36 month loan on it would leave the lender holding security that is twelve years old at the end. That is not a judgement on the bike. It is arithmetic about the tenure.
Which means a slightly newer vehicle at a slightly higher price is often the cheaper purchase, because it gets funded on better terms. Worth running both options past somebody before you commit.
How valuation works, and why it is not the price
The number that matters in a used two wheeler loan is not what the seller wants. It is what the lender's assessment says the bike is worth.
That assessment looks at model, year, kilometres, physical condition, ownership count and how clean the papers are. Then the loan is a percentage of that figure, typically seventy to eighty percent.
So there are two gaps between you and the bike, and both are yours to fund.
| Step | 2019 Splendor example |
|---|---|
| Seller asking price | Rs 52,000 |
| Lender valuation | Rs 44,000 |
| Loan at 75 percent of valuation | Rs 33,000 |
| Gap between asking and valuation | Rs 8,000 |
| Your twenty five percent share | Rs 11,000 |
| Cash you need on the day | Rs 19,000 |
Illustrative. Valuations move with condition and paperwork more than with the odometer alone.
Nineteen thousand, on a fifty two thousand rupee bike. That is the number nobody plans for, because the conversation in their head was about the fifty two.
There are three ways to close that gap and only one of them is any good.
You can save more before buying, which is obvious and correct. You can negotiate the asking price down toward the valuation, which works well once you have the valuation in hand, because it is the only genuinely objective number in the whole negotiation. Or you can borrow the difference somewhere expensive, which people do quietly and regret slowly.
Get the indicative valuation before you talk price. It costs you nothing and it changes the entire conversation.
The paperwork sequence, in the order it has to happen
Here is what Baljit did not know. These steps are not a checklist you can do in any order. Each one blocks the next.
The sequence, step by step
| Order | Step | Who does it | Realistic time |
|---|---|---|---|
| 1 | Clear seller's old loan, get NOC | Seller and their lender | 2 to 3 weeks after final payment |
| 2 | Remove hypothecation at RTO, Form 35 | Seller, at their RTO | 1 to 3 weeks |
| 3 | Lender valuation and inspection | You and your lender | 1 to 3 days |
| 4 | Loan sanction | Your lender | 3 to 7 working days |
| 5 | Payment and transfer, Forms 29 and 30 | Both parties | Same week |
| 6 | RC transfer into your name | RTO | 2 to 4 weeks |
| 7 | Insurance transferred to your name | You and the insurer | Within 14 days of transfer |
Punjab RTO timelines vary by district. Much of this can be tracked on the Parivahan portal.
Steps one and two are the entire problem. If the seller's RC still shows a finance company, nothing downstream can happen. An RC transfer filed while hypothecation is live gets rejected outright, because the RTO checks the vehicle record and flags it.
So ask one question on the very first visit, before you discuss price, before you ride it, before anything.
Show me the RC.
If there is a financier's name on it, ask whether the NOC is already in hand. If it is, fine, proceed. If it is not, understand that you are looking at a purchase that is a month or two away rather than a week, and price that delay into how much you are willing to pay and whether you wait at all.
The insurance step in row seven also gets skipped constantly. An insurance policy in the previous owner's name does not protect you. If something happens in that window, the claim goes to a person who no longer owns the vehicle. Fourteen days is the window and it is worth treating as a hard deadline.
Our full breakdown of used bike loan documents covers both halves of the file in more detail, yours and the seller's.
What a used bike actually costs in year one
The purchase is not the cost. This is the part that separates a good second hand buy from a bad one, and almost nobody calculates it.
| Item | Typical, commuter | Note |
|---|---|---|
| Cash gap at purchase | Rs 15,000 to 20,000 | Valuation gap plus your share |
| Transfer and RTO charges | Rs 1,000 to 2,500 | Varies by district |
| Fresh insurance | Rs 2,500 to 6,000 | Depends on cover chosen |
| Catch-up service | Rs 1,500 to 3,000 | Oil, filters, brakes, chain |
| Deferred wear parts | Rs 2,000 to 8,000 | Tyres and battery are the usual two |
| First year EMIs | As sanctioned | Higher rate than a new bike |
Indicative. A bike with a service book needs far less of the fourth and fifth rows.
Add the middle four rows and you get somewhere between seven and twenty thousand rupees, on top of everything you had already budgeted.
I am not saying this to put you off used bikes. I buy the argument for them and I have made it in print more than once. I am saying that the person who budgets for it has a good year and the person who does not has a bad one, and it is the same bike in both cases.
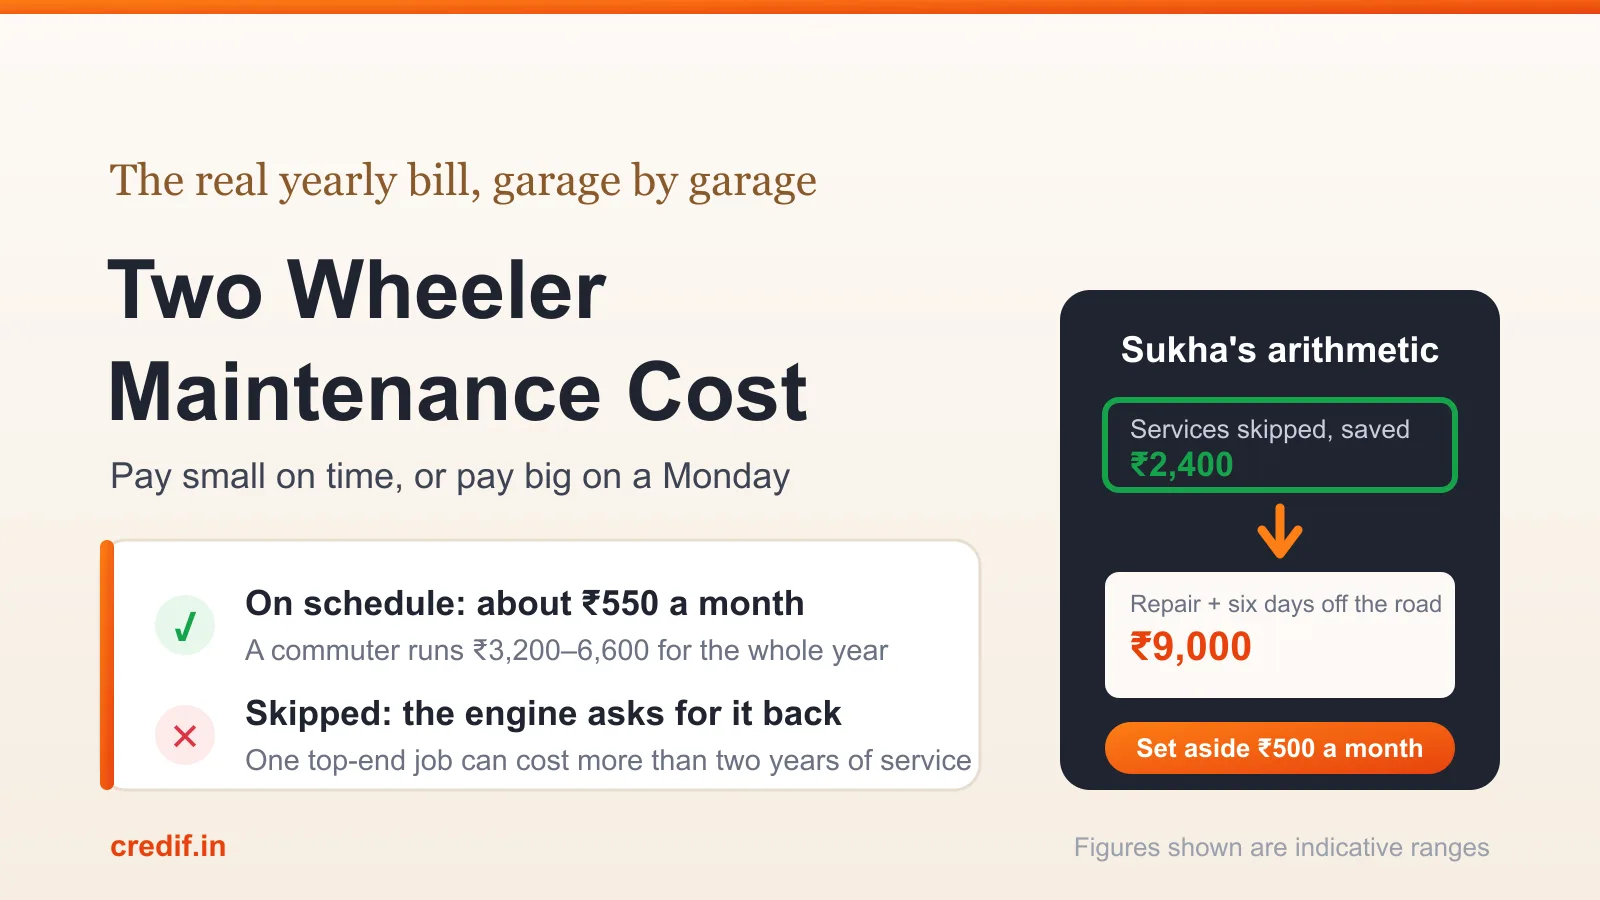
This is also why a stamped service book is worth real money at purchase. It moves the fourth and fifth rows toward their lower ends, and it lifts the valuation. Our piece on what two wheeler maintenance actually costs puts yearly figures on all of that.
Comparing a used bike against a new one?
The eligibility check takes a few minutes and needs no documents.
Check your eligibility →Five things I would check on any used bike in Punjab
Back to Baljit
The NOC eventually arrived. He got the hypothecation cleared, the RC transferred, insurance in his own name, and the whole thing settled by the end of June.
The bike, for what it is worth, was fine. It has done a few thousand kilometres since and needed a chain kit and one tyre.
What it cost him was not money. It was three months of owning something he could not prove was his, and a fairly unpleasant relationship with a man he now avoids in the market.
"Ab main pehle RC maangta hoon. Phir keemat."
Now I ask for the RC first. Then the price.
That is the only sentence from this article I would want anybody to actually remember.
Bottom line
A used two wheeler loan in Punjab is straightforward when the sequence runs in the right order and painful when it does not.
Ask for the RC before you discuss price. Check the age against what lenders will fund before you get attached. Get an indicative valuation, then negotiate against it. Budget the cash gap and the first year catch-up, not just the sticker. Move the insurance into your name inside two weeks.
The bike is usually the easy part. The paper is what costs people months.
Where Credifin fits
We finance used two wheelers and new two wheelers across 14 states and more than 200 locations, along with electric two wheelers, used cars and e-rickshaws.
Punjab is where we started, and second hand vehicle finance is a large part of what we do here. We read bank statements and actual income, delivery platform earnings included, which is why shopkeepers, riders, repairmen and first time borrowers get through with us where a strict salary slip process cannot read them at all. Moderate credit scores work at this ticket size, because the vehicle is the security.
Ask us for an indicative valuation before you agree a price with the seller. It is free, it takes very little time, and it is the single most useful thing you can do before handing over money.
Buying in a specific city? Our Ludhiana and Jalandhar pages cover the local picture in each.
Rather sit across a desk? Walk into your nearest branch.
Ready when you are
Used two wheeler finance on bank statements or platform earnings, across 14 states.
Apply now →Talk to Credifin
Credifin is an RBI registered NBFC financing new and used two wheelers, cars, e-rickshaws and EVs across India.
079651-74500 | info@credif.in
Find your nearest branch →
FAQs
How old a bike can I finance in Punjab?
Most lenders fund up to five years, and some go to seven for a vehicle in good condition with clean papers. The practical limit is that the bike should not be much past ten years old by the time the loan ends.
How much loan will I get on a second hand bike?
Usually seventy to eighty percent of the lender's valuation, not of the asking price. Those two numbers differ, so arrange the valuation before you finalise a price with the seller.
What if the seller's RC still shows a finance company?
That hypothecation must be cleared first, using the previous lender's NOC and Form 35 at the RTO. Nothing else can proceed until it is done, and it usually takes several weeks. Ask to see the RC on your first visit.
Do pending challans transfer to me?
Yes. Check the vehicle on the Parivahan portal before you buy. It is free and takes a couple of minutes, and unpaid challans can also hold up the RC transfer.
Is the interest rate higher on a used two wheeler loan?
Typically two to four percent above a new vehicle rate, because the security is older. Tenures are usually shorter as well, which pushes the EMI up a little more than people expect.
How long does the whole process take?
Three to seven working days for the loan decision, but the RC transfer and insurance change take another few weeks. If the seller needs to clear hypothecation first, add a month or more to all of it.
Do I need to change the insurance?
Yes, within fourteen days of the ownership transfer. A policy still in the previous owner's name will not protect you if you need to claim, whatever the seller says about it being valid.
Can I get a used bike loan with a low credit score?
Often yes, since the loan is secured and the amount is small. Expect a higher rate and a larger down payment. Bank statements showing regular income matter more here than the score alone does.