Two Wheeler Loan in Jalandhar: New vs Used, Real Rates, and What Your Quote Should Say
Vansh Budhiraja·05 September 2026
Ramanpreet is twenty three. Second year of a diploma, and three evenings a week he works at a packing unit near Basti Nau that ships cricket bats to buyers he will never meet.
His father has been in Dubai since 2019. Money arrives at home every month, reliably, in his mother's account.
So by any sensible measure the family can afford a bike. What they could not do was prove it in a way that fit the form, because the earner is four thousand kilometres away and the applicant was a student with a CIBIL score that did not exist yet.
He went to two showrooms on Nakodar Road. Both were friendly. Both said the same thing in slightly different words.
"Paise bahar se aate hain, loan yahin chahiye."
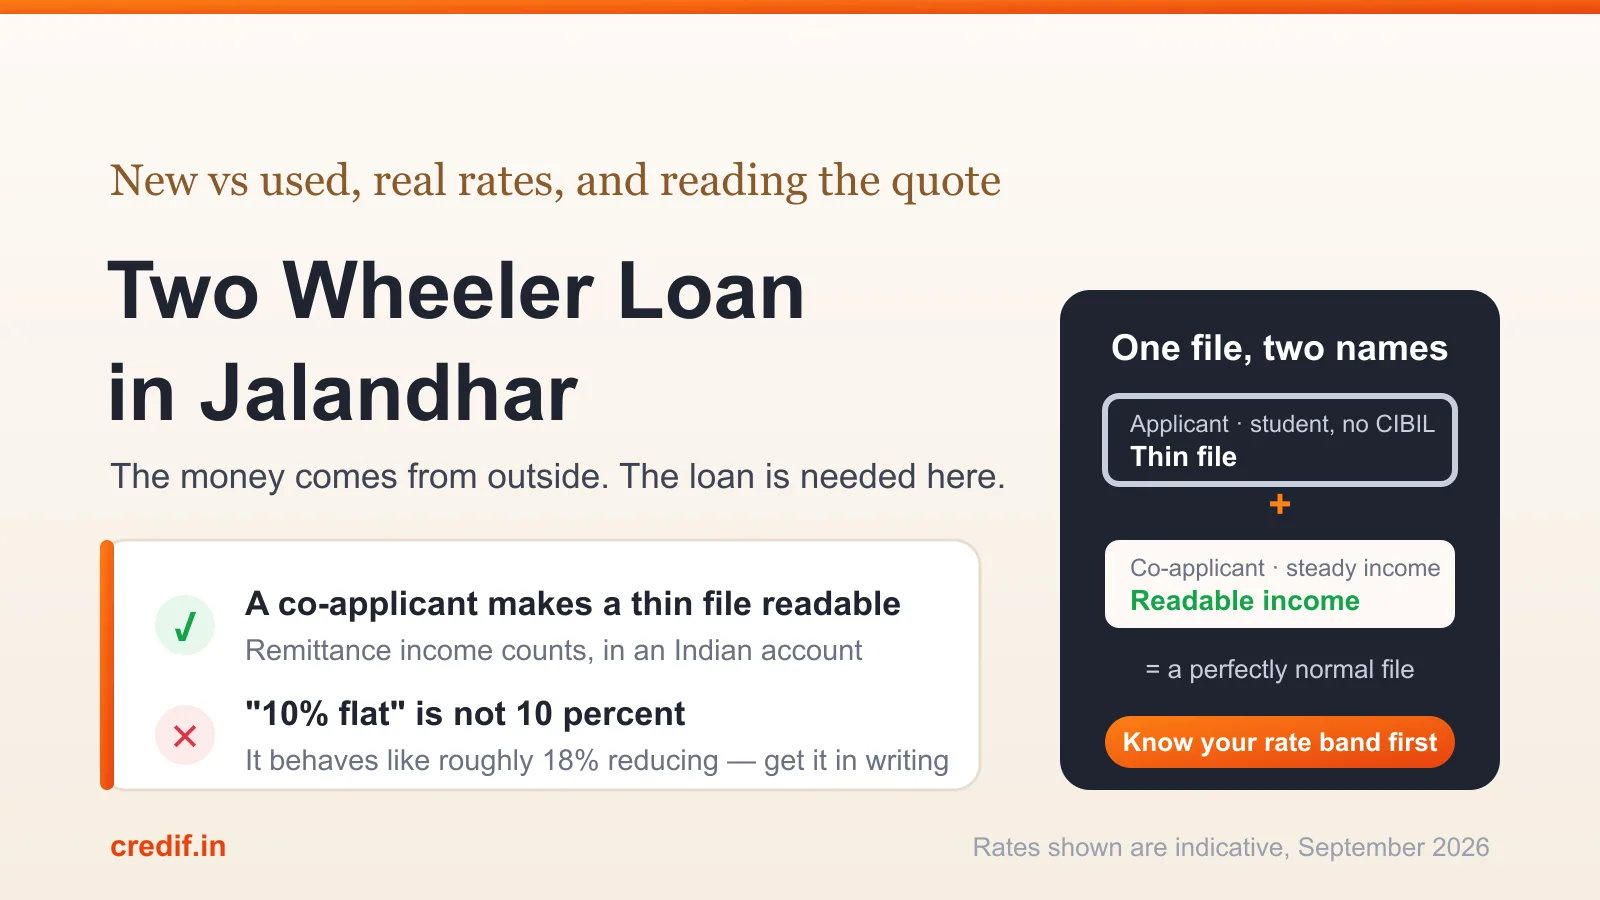
The money comes from outside. The loan is needed here.
That is a very Doaba problem and it has a straightforward answer, which I will get to. But it points at something bigger about buying a bike in this city, and it is the reason I wanted to write a Jalandhar version rather than a generic one.
Jalandhar's two wheeler market is unusually split. There is a thriving used trade here, far busier than in most Punjab cities of comparable size. Households often have one earner abroad and everybody else on paper as a dependent. And an enormous share of buyers are doing this for the first time in their life, which means they are making decisions without knowing what a normal decision looks like.
This guide covers the three things that actually decide what you pay. Whether you buy new or used. What rate your profile earns. And whether you read the quote before signing it.
Want to know your number before you talk to a dealer?
Credifin reads bank statements, remittances and real income. Clean file decided in 3 to 7 working days.
Check your eligibility →New or used, on the same budget
Almost every first-time buyer in Jalandhar asks this, and almost none of them ask it properly. The honest question is not which is cheaper. Both are cheap. The question is what a fixed amount of money buys you in each direction.
Say you have Rs 90,000 to spend on road, however you finance it.
What Rs 90,000 buys
| New | Used | |
|---|---|---|
| Typical machine | Hero HF Deluxe or TVS Jupiter, base variant, brand new | 2021 Pulsar 150 or 2022 Activa, 25,000 to 40,000 km run |
| Warranty | Full manufacturer cover, usually 5 years with extension | None, or whatever is left over |
| First year repairs | Near zero beyond scheduled service | Budget Rs 4,000 to 8,000 for catching up |
| Depreciation, year one | Steep. Twenty to twenty five percent gone | Gentle. The previous owner already took that hit |
| Finance | Widely available, better rates, longer tenures | Available, higher rate, shorter tenure, valuation applies |
| Paperwork risk | Nil | Real. RC, hypothecation, challans, chassis |
Indicative. Condition and history change the used column enormously.
Here is how I would actually decide it, and it is not about money at all.
Buy new if this is your first vehicle and nobody in your family can assess a used one. You are paying a premium for the absence of surprises, and for a first-time owner that premium is usually worth it.
Buy used if somebody around you genuinely knows bikes, and you want more machine than your budget allows new. A well-kept 150cc at ninety thousand is a much better vehicle than a new 100cc at the same price. It is also a bigger bet.
What I would not do is buy used because it seemed cheaper and then discover the reason it was cheap. Jalandhar's used market has plenty of good sellers and a fair number who are simply passing on a problem. Our checklist for used bike loan documents covers both halves, yours and the seller's.
What rate you actually get
Nobody publishes an honest version of this, so here is one. Two wheeler rates are set by how readable your income is and how long your credit history runs, far more than by how much you earn.
Rate bands, by profile
| Profile | Typical rate band | What moves it |
|---|---|---|
| Salaried, CIBIL 750 plus, 2 years in job | 9.5 to 12 percent | Clean history is the cheapest asset you own |
| Salaried, CIBIL 650 to 750 | 12 to 15 percent | One old default drags this more than income lifts it |
| Self-employed with GST or ITR | 12 to 16 percent | Filed returns pull you toward the lower end |
| Bank statement income, gig or shop | 14 to 18 percent | Regularity of credits matters more than the total |
| No credit history at all | 15 to 20 percent, or a co-applicant | First-time borrowers price high until they have a record |
| Used two wheeler, any profile | Add roughly 2 to 4 percent | The asset is older, so the security is weaker |
Indicative for September 2026. Actual offers vary by lender, ticket size and tenure.
Look at the spread. Between the top row and the fifth row is eight or nine percentage points, which on a Rs 80,000 loan over three years is roughly twelve thousand rupees of difference on the same bike.
That is the entire argument for spending three months preparing before you apply, rather than walking in on a Sunday because you felt like it.
And the fix for the last row is the thing Ramanpreet needed. A co-applicant.
The co-applicant route, and when to use it
A co-applicant is somebody who takes on the loan jointly with you. Their income counts, their credit record counts, and their signature sits next to yours on the repayment obligation.
For a large part of Jalandhar this is not a workaround, it is simply the correct structure.
Students. Homemakers. Young men whose household income arrives from abroad. People in their first six months of a job. Anyone with a thin file and a family member with a thick one.
Three things worth knowing before you go down this road.
The used bike valuation gap
If you go used, this is the single thing that catches people out, and it catches almost everyone the first time.
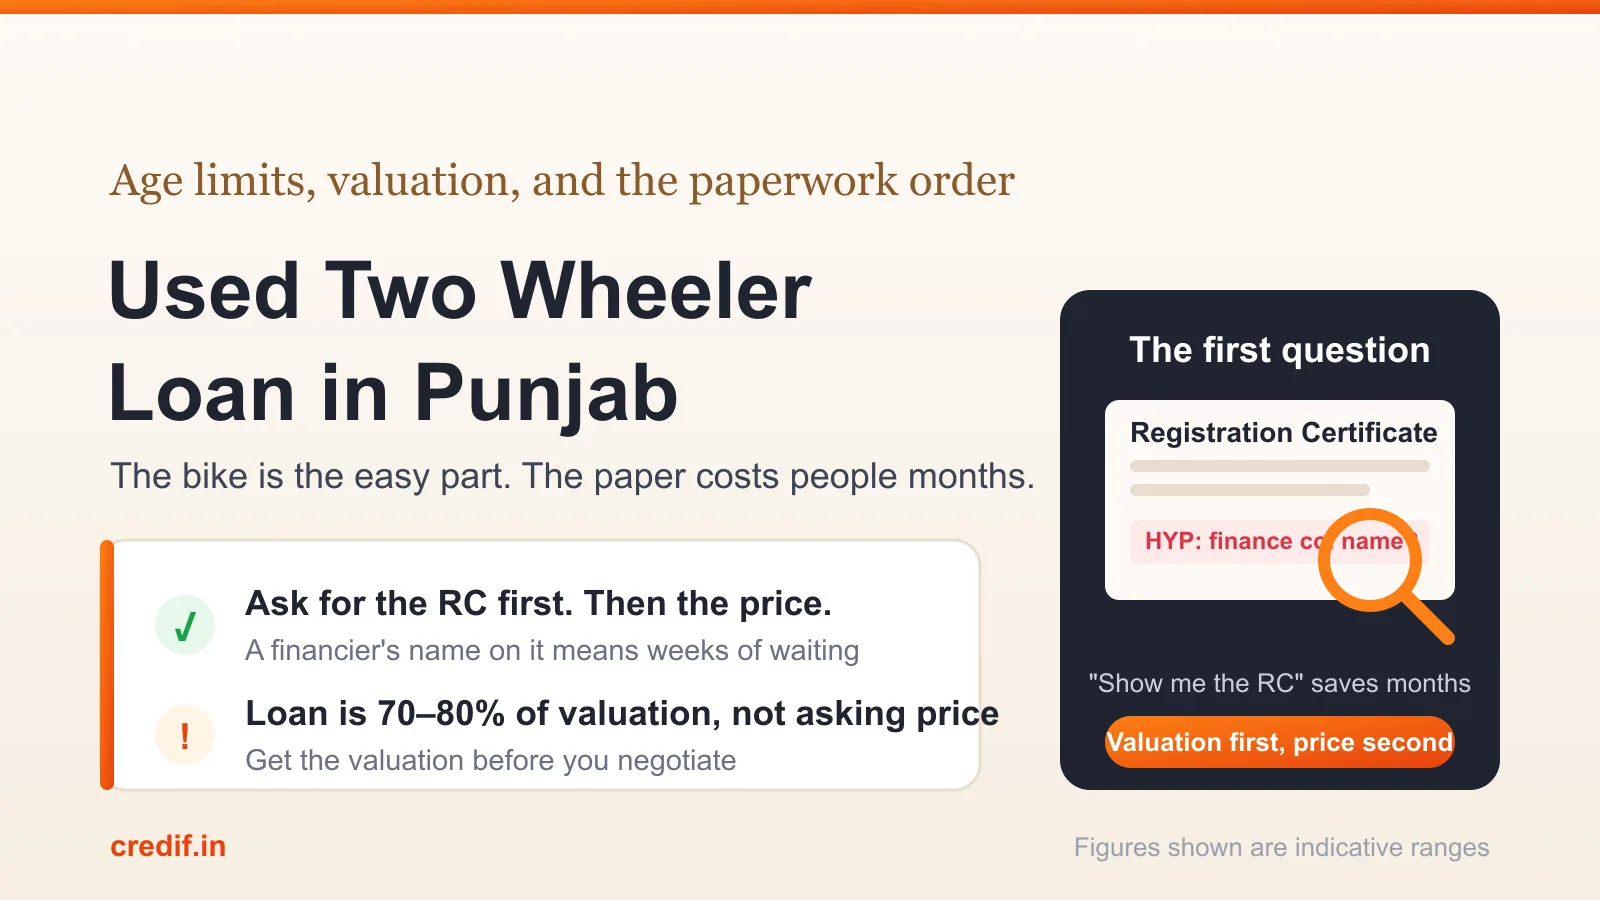
A lender does not fund the price you agreed with the seller. It funds a percentage of its own valuation of the vehicle. Those two numbers are rarely the same, and the difference comes out of your pocket on the day.
| Bike | Seller asking | Lender valuation | Loan at 75 percent | You pay |
|---|---|---|---|---|
| 2021 Pulsar 150 | Rs 62,000 | Rs 55,000 | Rs 41,250 | Rs 20,750 |
| 2022 Honda Activa | Rs 58,000 | Rs 54,000 | Rs 40,500 | Rs 17,500 |
| 2020 Splendor Plus | Rs 41,000 | Rs 34,000 | Rs 25,500 | Rs 15,500 |
Illustrative. Valuation depends on condition, kilometres, service record and paperwork.
Notice the third row. A seven thousand rupee gap between asking and valuation turns into a fifteen and a half thousand rupee cash requirement, because you are covering both the gap and the quarter that was never going to be financed.
So do it in this order. Get an indicative valuation first. Then negotiate. Walking into a price agreement before you know what the lender thinks the bike is worth is how people end up borrowing from a relative at the last minute, which is a bad way to start owning something.
Two things lift a used valuation more than people expect. A stamped service book, and a clean RC with hypothecation from the previous loan already removed. If the seller still has the finance company's name on the registration certificate, that has to be cleared before anything else can happen, and it takes weeks rather than days. Our Punjab used two wheeler guide walks through that full paperwork sequence step by step.
Buying used and want to know what it will value at?
Ask us for an indicative number before you agree a price.
Check your eligibility →Read the quote. Actually read it.
This is the least glamorous section here and it is the one that saves the most money.
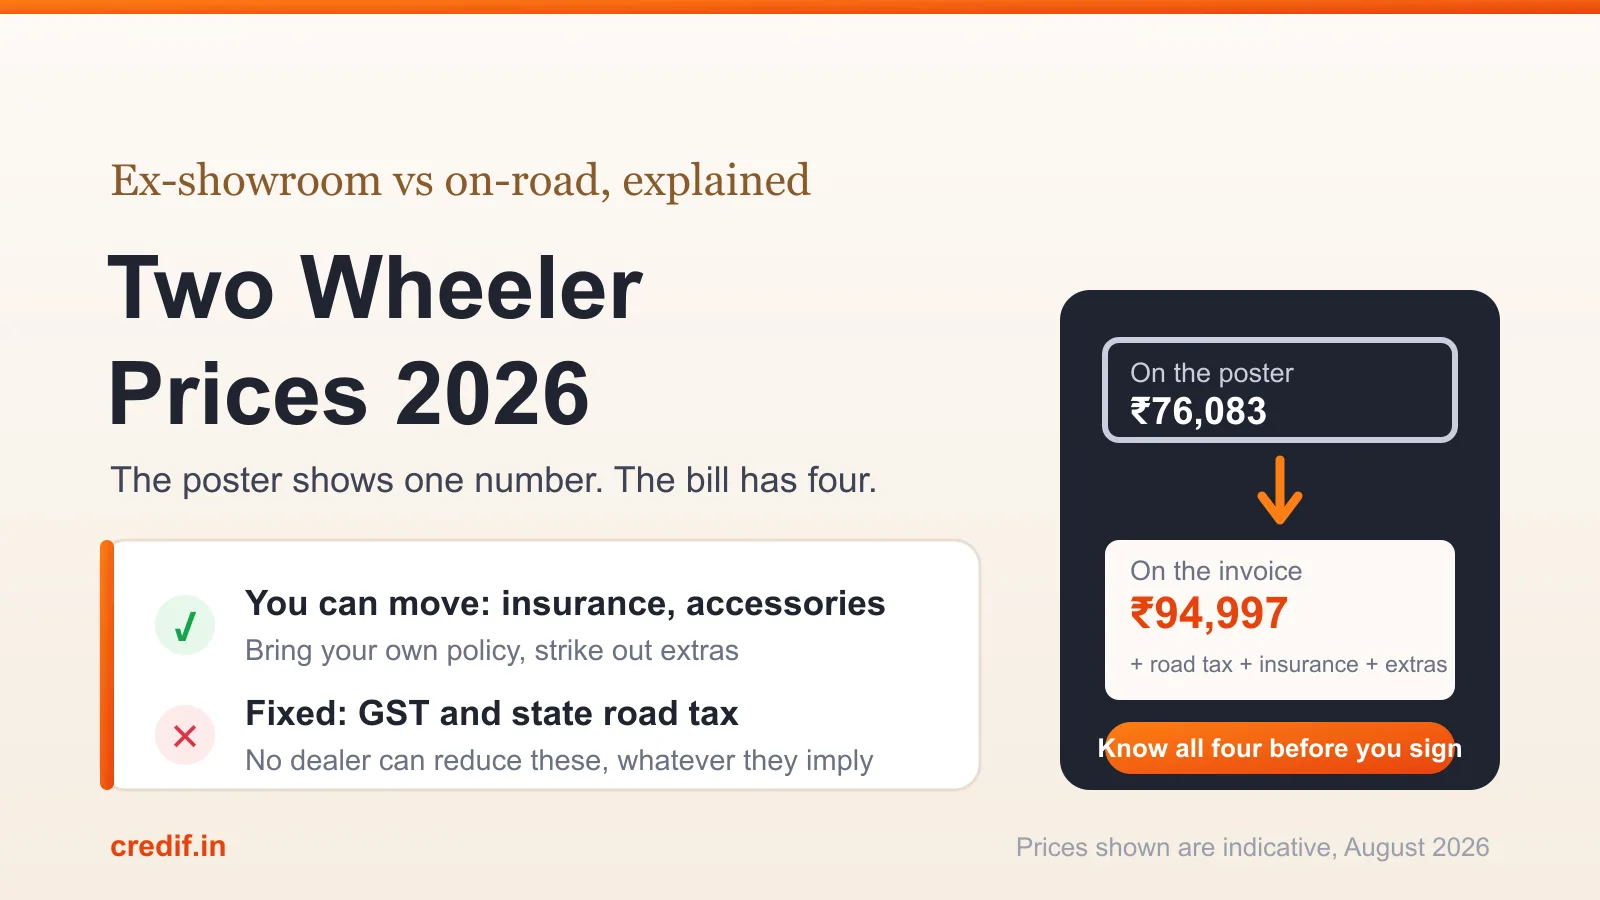
Before you pay a booking amount, you should be holding two documents. A written on-road breakup from the dealer, and a sanction letter from whoever is lending. Both of them should say specific things. Our breakdown of two wheeler prices covers the four numbers inside that on-road figure.
| Check | What you are looking for | Why it matters |
|---|---|---|
| On-road breakup | Ex-showroom, RTO, insurance and handling listed separately | Bundled totals hide accessories nobody ordered |
| Insurance line | Which policy, which insurer, what cover | You are allowed to bring your own and usually should |
| Interest rate type | Reducing balance, stated clearly | A flat rate sounds lower and costs considerably more |
| Processing fee | Rupee amount, not a vague percentage | It is negotiable more often than people try |
| Foreclosure terms | Charge to close early, and after how long | Matters if a bonus or a good season lands |
| Tenure and EMI count | Exact months and exact instalment | Verbal figures drift by the time papers are drawn |
Ask for all of it in writing before the booking amount, not after. The leverage is entirely on your side until you pay.
The flat versus reducing distinction deserves its own sentence, because it is where the real money hides. A flat rate charges interest on the original amount for the whole tenure, even as you pay the principal down. Ten percent flat is not ten percent. It works out closer to eighteen. RBI requires banks to quote on reducing balance, and most reputable NBFCs do too, but at the dealership counter the word is sometimes used loosely. Ask which one it is and ask them to write it down.
Back to Ramanpreet
He applied jointly with his mother.
Her account had six months of clean inward remittances and a small recurring deposit she had been running since before any of this came up. Between the two of them the file read perfectly normally, which it always was, just not in the shape the first form wanted.
He bought used in the end. A 2021 Pulsar, valued at Rs 55,000 against an asking price of Rs 60,000 that he talked down to Rs 57,500 once he knew what the lender's number was. Loan of Rs 41,000 over 30 months.
The bike had a service book. That is genuinely why he picked it over a slightly newer one, which two months earlier he would not have thought to ask about.
"Pehli baar samajh aaya ki kaagaz bhi paise hai."
The first time I understood that paperwork is money too.
His EMI is Rs 1,620. In roughly two and a half years he will be twenty six with a closed loan on his credit record, which is worth more to him over the next decade than the bike is.
Bottom line
A two wheeler loan in Jalandhar comes down to three decisions and the order you make them in.
Decide new or used on the basis of who around you can judge a used bike, not on price alone. Work out what rate band your profile falls into, and if it is the bottom one, use a co-applicant rather than accepting a bad rate. If you go used, get the valuation before you agree the price. And read the breakup and the sanction letter properly before any money changes hands, because that is the last moment you hold all the leverage.
Buying in Ludhiana instead? Our guide to two wheeler loans in Ludhiana covers the same ground for that city's borrower profiles.
Where Credifin fits
We are headquartered in Jalandhar, so this city is not a market we read about in a report.
We finance new two wheelers and used two wheelers across 14 states and more than 200 locations, along with electric two wheelers, used cars and e-rickshaws.
We read bank statements and actual income, remittances and delivery platform earnings included. That is why students with a co-applicant, shopkeepers, riders and first time borrowers get approved with us when a strict salary slip process cannot read them at all. Moderate credit scores work at this ticket size, because the vehicle is the security.
Apply online and a clean file is decided in 3 to 7 working days. We will also give you an indicative number before you agree a price with the seller or the dealer, which is the right order to do this in.
Buying electric? Our EV loan guide for Jalandhar covers scooters, e-rickshaws and electric cars.
Visit Us in Jalandhar
Rather do this across a desk? Our Mahavir Nagar branch is next to Chirayu TVS showroom, or find your nearest office.
Credifin Limited
87, Radio Colony, New Jawahar Nagar, Mahavir Nagar
Jalandhar, Punjab 144001
079651-74500 | info@credif.in
View on Google Maps →
Ready when you are
New and used two wheeler finance on bank statements, remittances or platform earnings.
Apply now →Talk to Credifin
Credifin is an RBI registered NBFC financing new and used two wheelers, cars, e-rickshaws and EVs across India.
079651-74500 | info@credif.in
Find your nearest branch →
FAQs
Can a student get a bike loan in Jalandhar?
Usually only with a co-applicant who has income and a credit record. A parent or an elder sibling works. Once the loan runs clean for a couple of years you will have a record of your own, which is the real long term benefit of doing it this way.
Does money sent from abroad count as income?
Yes, if it arrives in an Indian bank account and shows a regular pattern over six months or more. The account holder is usually the co-applicant. Cash carried home on visits cannot be assessed, however much it is.
What interest rate should I expect?
Roughly 9.5 to 12 percent for salaried applicants with a strong credit record, 14 to 18 percent for bank statement and gig income, and two to four percent more on a used vehicle. A co-applicant with a good score moves you toward the lower end.
Why is the loan amount less than the price of the used bike?
Because the lender funds a percentage of its own valuation, not the seller's asking price. Get that valuation before you negotiate, so you know what cash you actually need on the day.
What is the difference between flat and reducing interest?
Flat charges interest on the full original amount throughout, so ten percent flat behaves like roughly eighteen percent reducing. Always confirm in writing which one is being quoted.
Can I close the loan early?
Generally yes, usually after a minimum number of instalments, sometimes with a foreclosure charge. Ask for the terms before signing rather than assuming, since they vary quite a bit between lenders.
What if the seller's RC still shows a finance company?
That hypothecation has to be removed first, with the previous lender's NOC and a Form 35 at the RTO. Any transfer attempted before that gets rejected. Build the extra weeks into your plan or choose a bike with clean papers.
Is buying used a mistake for a first bike?
Not a mistake, but a bigger bet. If nobody around you can properly assess a used machine, the warranty on a new one is worth what it costs. If you have someone who knows bikes, used gets you considerably more vehicle for the money.
This might catch your interest