Two Wheeler Loan in Ludhiana: EMI, Documents and the Real Approval Time
Vansh Budhiraja·08 September 2026
Manpreet supplies thread and trimmings to four hosiery units off Gill Road. Small shop, one shutter, a boy who helps him on delivery days.
He clears somewhere between forty and fifty five thousand a month. Has done for six years. He wanted a Splendor so he could stop paying an autowala two hundred rupees a day to move sample bundles across town, which even on a slow month is six thousand gone.
The bank near his shop took his file on a Tuesday and returned it on a Friday.
No ITR. That was the whole reason.
His money was real. It arrived in his account, most of it, in amounts you could set your watch by. But the form had a box marked income proof and he had nothing to put in it that the system recognised.
"Bank ne kaha income proof lao. Income to thi, proof nahi tha."
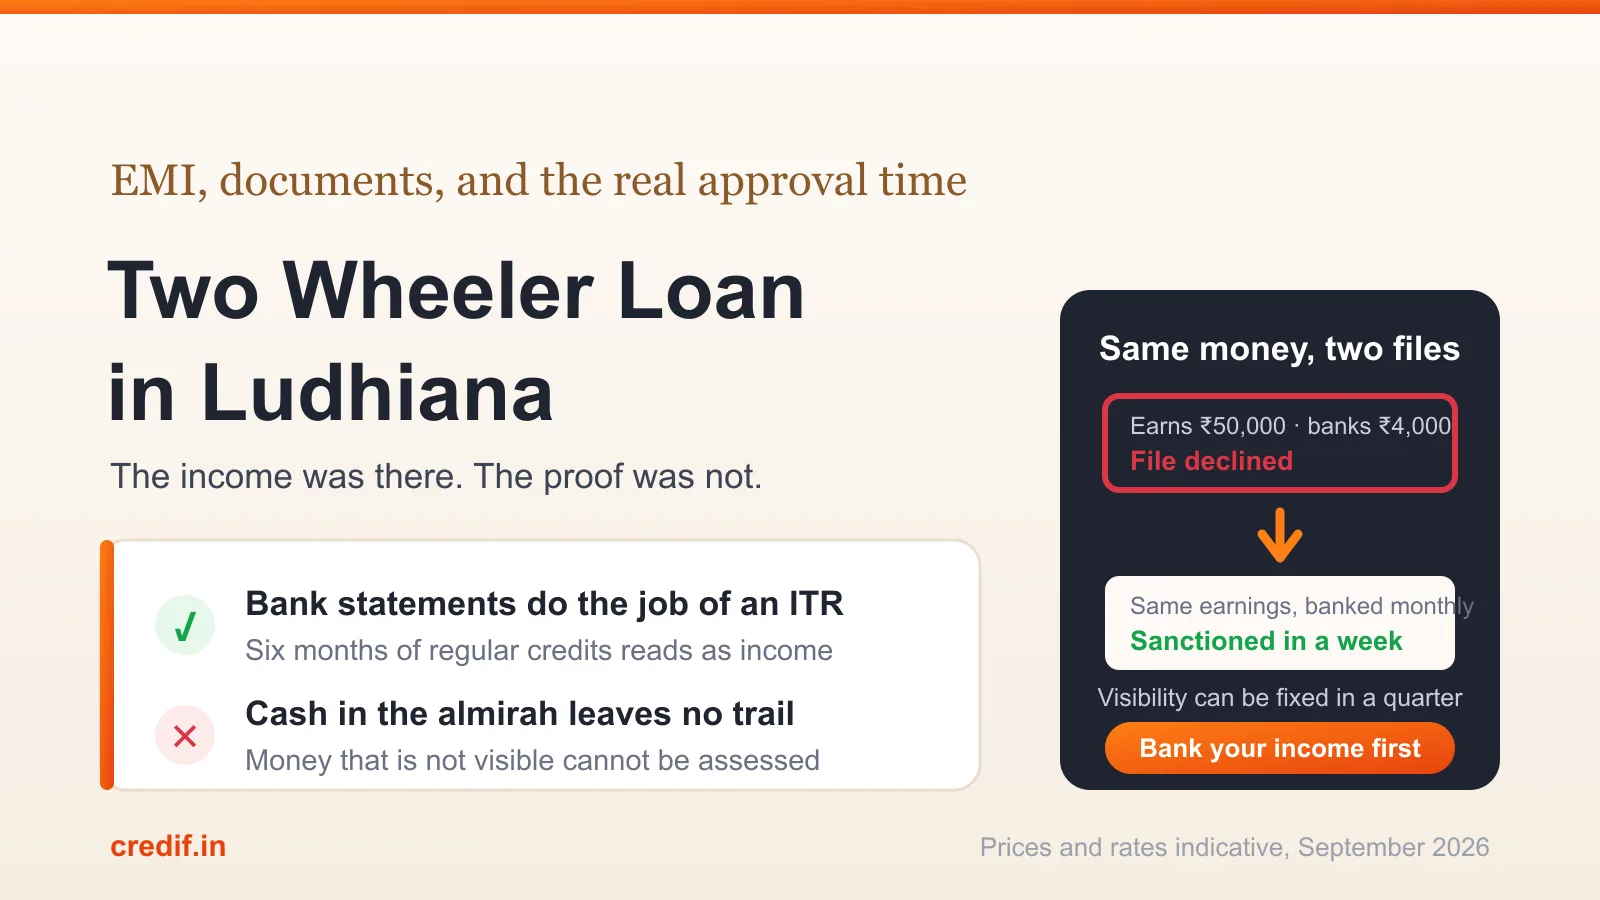
The bank asked me for proof of income. The income was there. The proof was not.
I hear a version of this most weeks, and almost always from Ludhiana. This city runs on units, job work, commission, cash settled on the twentieth. A two wheeler loan here fails far more often on documentation than on affordability, and those are completely different problems with completely different fixes.
So this is the local version. What a bike actually costs on road in Punjab, what the EMI works out to, which papers move your file and which ones waste your week, and where applications in this city get stuck.
Buying a bike and want a straight answer before you talk price with the dealer?
Credifin reads bank statements and real income, not just salary slips. Clean file decided in 3 to 7 working days.
Check your eligibility →Why Ludhiana specifically
Ludhiana has more small enterprise per square kilometre than almost anywhere in north India, and that shapes who walks into a showroom.
Hosiery. Cycle parts. Hand tools. Dyeing units. Fabrication sheds behind Focal Point. Thousands of people earning perfectly good money inside businesses that keep minimal books, or working for those businesses on wages that get topped up in cash.
Add the delivery economy, which has grown fast here, and the students around PAU and GNDEC who want their own vehicle and have no credit history whatsoever.
Now look at what mainstream underwriting is built to read. Three months of salary slips. Two years of filed returns. Form 16. A CIBIL score with at least a couple of years behind it.
Most of this city fails that test on paper while passing it comfortably in practice. That mismatch is the single biggest reason a two wheeler loan gets declined in Ludhiana, and it has nothing to do with whether the applicant can pay.
Understanding that changes what you do. You stop trying to look like a salaried applicant. You start building a file that shows money moving.
What a bike actually costs here
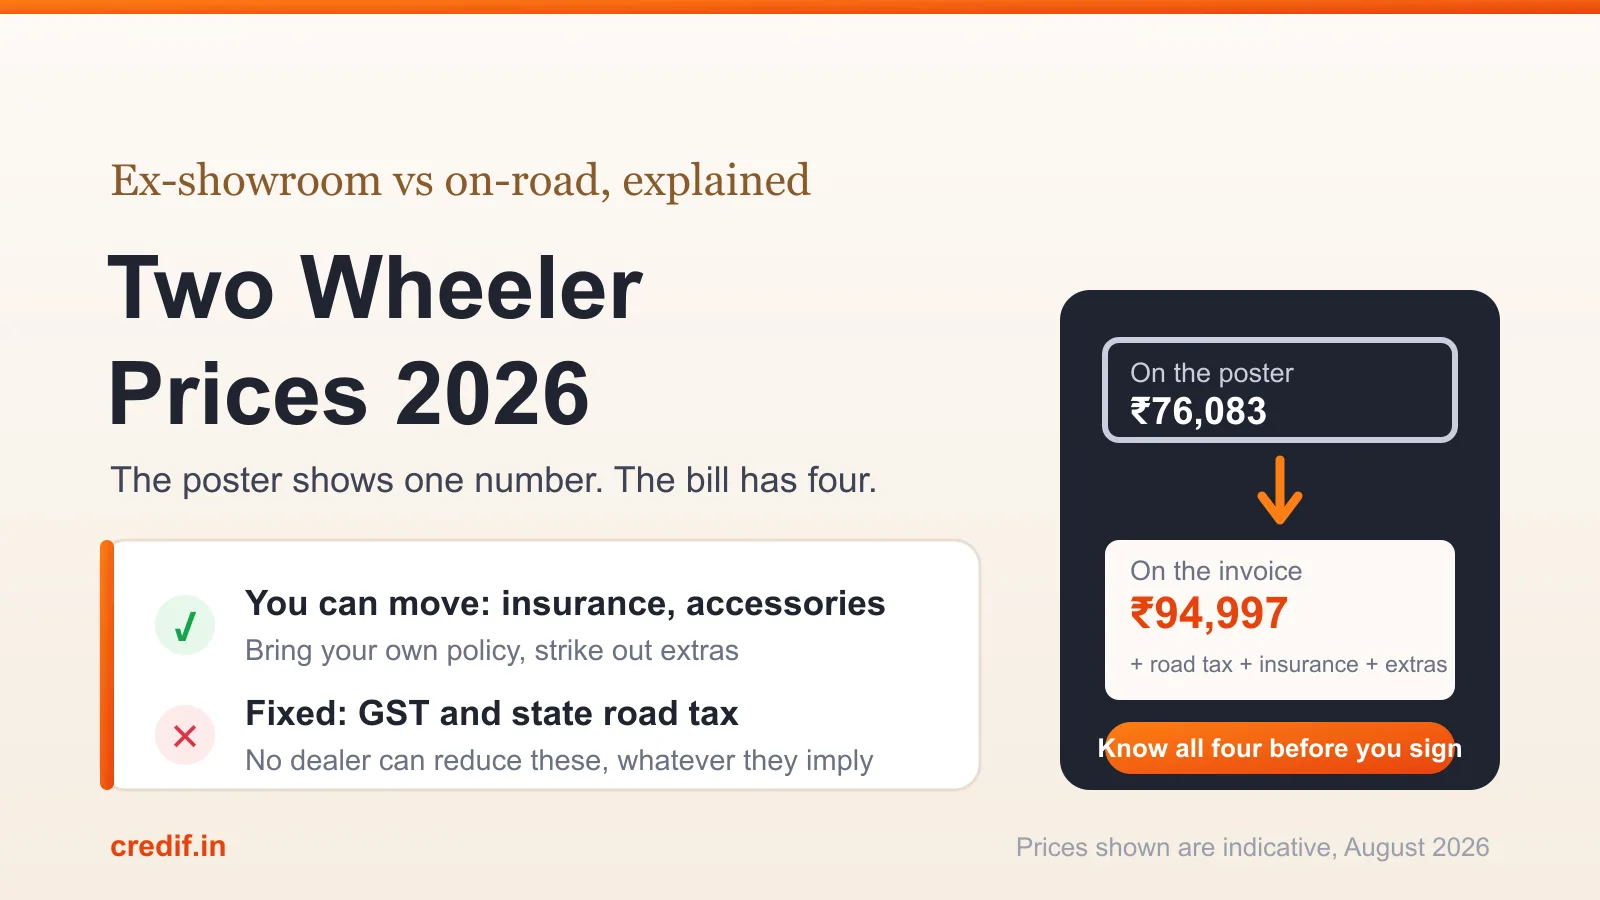
Before the loan, the price. Punjab charges motor vehicle tax as a percentage of ex-showroom, and it sits in the middle of the national range, well under Karnataka and a little above Delhi. Insurance in Ludhiana runs close to the north India average.
On-road prices in Ludhiana
| Model | Ex-showroom | Approx on-road, Ludhiana |
|---|---|---|
| Hero HF Deluxe | Rs 68,855 | Around Rs 81,000 |
| TVS Jupiter 110 | Rs 74,125 | Around Rs 87,500 |
| Honda Activa | Rs 76,083 | Around Rs 89,500 |
| Hero Splendor Plus | Rs 77,123 | Around Rs 90,500 |
| Suzuki Access 125 | Rs 79,899 | Around Rs 93,500 |
| Bajaj Pulsar 125 | Around Rs 88,000 | Around Rs 1,03,000 |
Indicative, September 2026, base variants. Road tax, registration and insurance vary by variant and by dealer. Get your own quote in writing.
Two points worth holding on to.
Your loan is sanctioned against the on-road figure, not the poster number. Somebody who has budgeted around a Rs 76,000 Activa is actually financing something closer to Rs 89,500, and if they have kept ten thousand aside as down payment, the gap is bigger than they think. We broke the whole ex-showroom versus on-road business down properly in our guide to two wheeler prices in India.
And top variants move these numbers by eight to fifteen thousand. Decide the variant before you work out the EMI, not after, because that is the order in which the maths actually runs.
The EMI, in plain numbers
Loan to value on a new two wheeler typically lands between 75 and 90 percent depending on your profile, so plan for a down payment of roughly ten to twenty five percent.
| On-road | Down payment | Loan amount | EMI, 24 months | EMI, 36 months |
|---|---|---|---|---|
| Rs 81,000 | Rs 16,000 | Rs 65,000 | Rs 3,140 | Rs 2,230 |
| Rs 89,500 | Rs 17,500 | Rs 72,000 | Rs 3,480 | Rs 2,470 |
| Rs 90,500 | Rs 12,500 | Rs 78,000 | Rs 3,770 | Rs 2,675 |
| Rs 1,03,000 | Rs 18,000 | Rs 85,000 | Rs 4,105 | Rs 2,915 |
| Rs 1,15,000 | Rs 20,000 | Rs 95,000 | Rs 4,590 | Rs 3,260 |
Illustrative at around 13 percent reducing. Your rate depends on income type, credit history and lender. Strong salaried files in Ludhiana do see single digit rates.
Compare rows three and four for a second. Rs 78,000 borrowed against Rs 85,000 borrowed is a difference of Rs 240 a month over three years. Genuinely small.
Now compare the same row across tenures. Rs 78,000 costs Rs 3,770 a month for two years or Rs 2,675 for three, and the three year version hands roughly seven thousand extra to the lender over the life of the loan.
Neither column is the right answer. The right answer is the largest EMI your month absorbs without you dipping into anything. In a city where income arrives in lumps rather than on the first, that usually means being a bit more conservative than the calculator suggests, and I would rather you did that than found out in month nine.
One habit worth copying from borrowers who never have trouble. Work out the EMI, then pay yourself that amount into a separate account for two months before you apply. If it hurts, you have your answer for free.
Documents that actually move a file
This is where Ludhiana applications live or die. The list changes completely depending on how you earn.
By how you earn
| Your profile | What works | What slows you down |
|---|---|---|
| Salaried, unit or factory | 3 months slips, 6 months bank statement, Aadhaar, PAN | Salary paid partly in cash with no matching credit |
| Shop owner or trader | 6 to 12 months bank statement, GST returns if you have them, shop proof | No ITR is manageable. A quiet account is not |
| Job work or commission | 6 months statement showing regular credits, buyer confirmation | Cash kept at home instead of banked |
| Delivery rider | In-app earnings report, 6 months statement, Aadhaar, PAN, DL | Earnings withdrawn instantly and spent in cash |
| Student or first job | Co-applicant with income, Aadhaar, PAN, college proof | Applying alone with no history at all |
Standard KYC applies to everyone. Address on Aadhaar should match where you actually live, and this one detail fails more files than it has any right to.
Read that right hand column again. Almost every entry describes the same thing. Money that exists but leaves no trail.
The fix is unglamorous and it works. Bank your income. Not all of it, not overnight, just enough that six months from now a statement shows a pattern instead of a desert. A trader depositing Rs 30,000 a month in reasonably regular amounts is a far stronger applicant than one who genuinely earns Rs 60,000 and deposits Rs 4,000.
On credit scores, moderate ones are workable at this ticket size because the vehicle is the security. Expect a higher rate and a bigger down payment rather than a flat no. Our piece on getting a loan at a 600 CIBIL score covers where the real cut-offs sit.
How long it takes, honestly
| Stage | What happens | Time |
|---|---|---|
| Eligibility check | Indicative amount, no documents needed | Minutes |
| Application and KYC | Aadhaar, PAN, address, basic details | Same day |
| Income assessment | Statement and income documents reviewed | 1 to 3 working days |
| Sanction | Amount, rate and tenure confirmed in writing | 3 to 7 working days total |
| Disbursal to dealer | Paid against invoice, vehicle released | 1 to 2 days after sanction |
Clean file. Missing or mismatched documents add days, and a name spelt differently across PAN and Aadhaar adds more than people expect.
Dealers in Ludhiana will often promise same day approval, and for a salaried applicant with tidy papers that is frequently true. The thing nobody mentions is that speed and price are two different conversations. Convenience at the counter is not the same as the cheapest money available to you, and it takes one comparison to find out which you are getting.
Five ways people here lose money on this
Taking the finance the showroom puts in front of them. It is quick, and it is quick because it is sitting right there. Get one outside quote. If the dealer offer wins, take it knowing it won.
Applying at four places in the same fortnight. Every application leaves a footprint. A cluster of them inside a few weeks reads as distress to the next lender and your file gets harder, not easier. Pick your two best options.
Arriving without six months of statements. The most common reason an application in this city stalls is not rejection. It is waiting while somebody chases paper he could have collected in an afternoon.
Borrowing on the ex-showroom figure. You finance the on-road number. Budget on that and the down payment conversation stops being a shock.
Forgetting the running cost. Service, wear parts and a set of tyres somewhere in year three. Our breakdown of what two wheeler maintenance actually costs puts a real yearly figure on it, and it is smaller than most people fear but larger than zero, which is what most people budget.
Comparing two models and want the monthly on each?
The eligibility check takes a few minutes and needs no documents at all.
Check your eligibility →Back to Manpreet
He got the Splendor. Roughly five weeks after the bank sent him away, which is not fast, though most of that delay was his own.
What changed was small. He started putting his shop collections into his current account instead of the almirah. Four months of that and his statement finally showed what his business had been doing all along. He brought a GST return, a rent receipt for the shop and a WhatsApp order history from two of the hosiery units he supplies.
Sanctioned Rs 72,000 over 36 months. Down payment of seventeen and a half thousand, most of it money he had already saved for the autowala he no longer pays.
"Paisa wahi tha. Bas ab bank ko dikhta hai."
The money was the same. Now the bank can see it.
That sentence is the whole article. Almost nobody in this city has an income problem. They have a visibility problem, and unlike income, visibility can be fixed in a quarter.
Bottom line
A two wheeler loan in Ludhiana is rarely decided by whether you can afford the bike. It is decided by whether the money you earn shows up somewhere a lender can read.
Bank your income for a few months before you apply. Collect six months of statements before you walk in. Budget on the on-road price, not the board. Get one quote outside the showroom. Pick the EMI your slowest month can carry, not your best one.
Do that and the approval is the easy part.
Where Credifin fits
We finance new two wheelers and used two wheelers across 14 states and more than 200 locations, along with electric two wheelers, used cars and e-rickshaws.
Ludhiana is home ground for us. We read bank statements and actual income, delivery platform earnings included, which is why traders, job workers, riders and first time borrowers get approved with us when a strict salary slip process cannot read them at all. Moderate credit scores work at this ticket size, because the vehicle itself is the security.
Apply online and a clean file is decided in 3 to 7 working days. If something is missing we tell you what it is rather than leaving you guessing. We will also tell you what you qualify for before you agree a price with the dealer, which is the right order to do this in.
Buying electric instead? Our EV loan guide for Ludhiana covers the same ground for electric scooters and e-rickshaws.
Visit Us in Ludhiana
Rather sit across a desk from an actual person? Walk into our Pakhowal Road branch, or find your nearest office.
Credifin Limited
First Floor, SCO 668, New Lajpat Nagar
Pakhowal Road, Ludhiana, Punjab 141002
079651-74500 | info@credif.in
View on Google Maps →
Ready when you are
New and used two wheeler finance on bank statements or platform earnings.
Apply now →Talk to Credifin
Credifin is an RBI registered NBFC financing new and used two wheelers, cars, e-rickshaws and EVs across India.
079651-74500 | info@credif.in
Find your nearest branch →
FAQs
Can I get a bike loan in Ludhiana without an ITR?
Yes, at most NBFCs. Six to twelve months of bank statements showing regular credits does the same job. Banks are stricter about returns. If you have GST filings, bring those too, since they strengthen a self-employed file considerably.
What is the minimum income needed?
Broadly Rs 10,000 to 15,000 a month, though what matters more is whether that income is visible in an account and whether your existing EMIs leave room. Two people on the same earnings get different answers depending on what they already owe.
How much down payment should I plan for?
Ten to twenty five percent of the on-road price. On a Rs 90,000 bike that is roughly Rs 9,000 to Rs 22,500. A larger down payment lowers both the EMI and the total interest, and for a thin file it also improves the odds of approval.
Will the dealer arrange it faster than applying directly?
Sometimes, for salaried applicants with clean papers. Speed is not the same as cost. One outside quote tells you what the convenience is actually worth, and it takes a few minutes.
Can delivery riders get approved?
Yes. In-app earnings reports from Zomato, Swiggy, Blinkit and most aggregators are accepted as income proof now. Pair that with a bank statement showing the payouts landing and it is a workable file.
What if a bank has already rejected me?
A bank decline is not a market decline. Different lenders read different things, and NBFC underwriting is built for irregular income. Just avoid firing off applications everywhere at once, because the enquiries stack up and count against you.
Can I finance a second hand bike here?
Yes, though the loan is a share of the lender's own valuation rather than the asking price. Get an indicative valuation before you agree a number with the seller, and check that hypothecation from any earlier loan has been cleared on the RC.
How long before I can ride it away?
Three to seven working days on a clean file, plus a day or two for disbursal against the dealer invoice. The delays that actually happen are almost always missing documents rather than slow decisions.
This might catch your interest