EV Scooter Loan in India 2026: Interest Rates, EMI & Best Models to Finance
Vansh Budhiraja·Last Updated
Petrol crossed Rs 97 a litre in most of Punjab last week. My uncle, who drives a 2019 Activa to his shop in Model Town every day, did a back-of-envelope thing on his Saturday morning. 25 km daily run, plus weekend trips, plus the occasional family errand. About 1,400 rupees a month just on petrol. He hadn't thought about it as a number until then. He has now.
That's the conversation happening in every middle-class household in India in 2026. Petrol cost is no longer the background hum it used to be. It's the line item people actively try to escape.
Which is why EV scooters are everywhere now. Ola, Ather, TVS iQube, Bajaj Chetak, Hero Vida, Honda Activa e:, even some Chinese brands trying to break in. The vehicles are good now. The charging infrastructure is improving (slowly). And the financing has finally caught up to where regular two-wheeler loans were 5 years ago.
This guide is for whoever's seriously considering the switch and wants to understand the loan side properly before walking into a showroom.
Already picked your scooter?
Credifin's EV two-wheeler loan reads bank statements and platform payouts, not just salary slips. Decision on a clean file in 3 to 7 working days.
Check your eligibility →What an EV scooter actually costs in 2026
On-road prices, ballpark, depending on city:
Popular EV scooters, 2026 (approx)
| Model | Ex-showroom (Approx) | On-Road Delhi (Approx) | Range Claim |
|---|---|---|---|
| TVS iQube ST | Rs 1,40,000 | Rs 1,55,000 | 145 km |
| Bajaj Chetak 3503 | Rs 1,20,000 | Rs 1,35,000 | 153 km |
| Ola S1 Pro Gen 3 | Rs 1,35,000 | Rs 1,50,000 | 195 km |
| Ather 450X (3.7 kWh) | Rs 1,52,000 | Rs 1,68,000 | 161 km |
| Hero Vida V2 Plus | Rs 1,20,000 | Rs 1,34,000 | 143 km |
| Honda Activa e: | Rs 1,17,000 | Rs 1,31,000 | 102 km |
Prices move with variant, city and subsidy, so confirm the current quote with your dealer.
Range claims are ARAI numbers, which means real-world you'll get 75 to 85 percent of that. An Ather 450X claiming 161 km will give you a real 125 to 135 km in city use. Account for it.
EV scooter loan interest rates in 2026
Two-wheeler loans for EVs used to be more expensive than petrol scooters in 2022-23. Lenders weren't sure about resale value. That gap has closed now. Most banks treat EV scooters the same as petrol ones for financing purposes, with some even offering green vehicle discounts of 25 to 50 basis points.
EV scooter loan rates by lender type
| Lender Type | Interest Rate Range | Tenure | Max LTV |
|---|---|---|---|
| Private banks | 12% to 14% | Up to 4 years | Up to 95% |
| Public sector banks (green vehicle schemes) | 11.5% to 13.5% | Up to 4 years | Up to 90% |
| NBFCs (including Credifin) | 13% to 17% | 2 to 3 years | Up to 100% |
| Dealer-tied financing | 14% to 18% | 2 to 3 years | Up to 90% |
| Manufacturer (captive) financing | 13% to 16% | Up to 3 years | Up to 95% |
Working range you should aim for: 12 to 18 percent. Some public sector banks have green vehicle loan schemes that drop to 11.5 percent for the right customer profile. NBFCs go higher but accept lower CIBIL and informal income. These are indicative market ranges, not an offer from any lender.
EMI math at typical loan amounts
Most EV scooters land in the 1.3 to 1.7 lakh on-road range. Here's what monthly EMIs look like.
Monthly EMI at an indicative 15 percent
| Loan Amount | 24 Months | 36 Months | 48 Months |
|---|---|---|---|
| Rs 1,00,000 | Rs 4,849 | Rs 3,467 | Rs 2,783 |
| Rs 1,20,000 | Rs 5,818 | Rs 4,160 | Rs 3,340 |
| Rs 1,50,000 | Rs 7,273 | Rs 5,200 | Rs 4,175 |
| Rs 1,80,000 | Rs 8,728 | Rs 6,240 | Rs 5,010 |
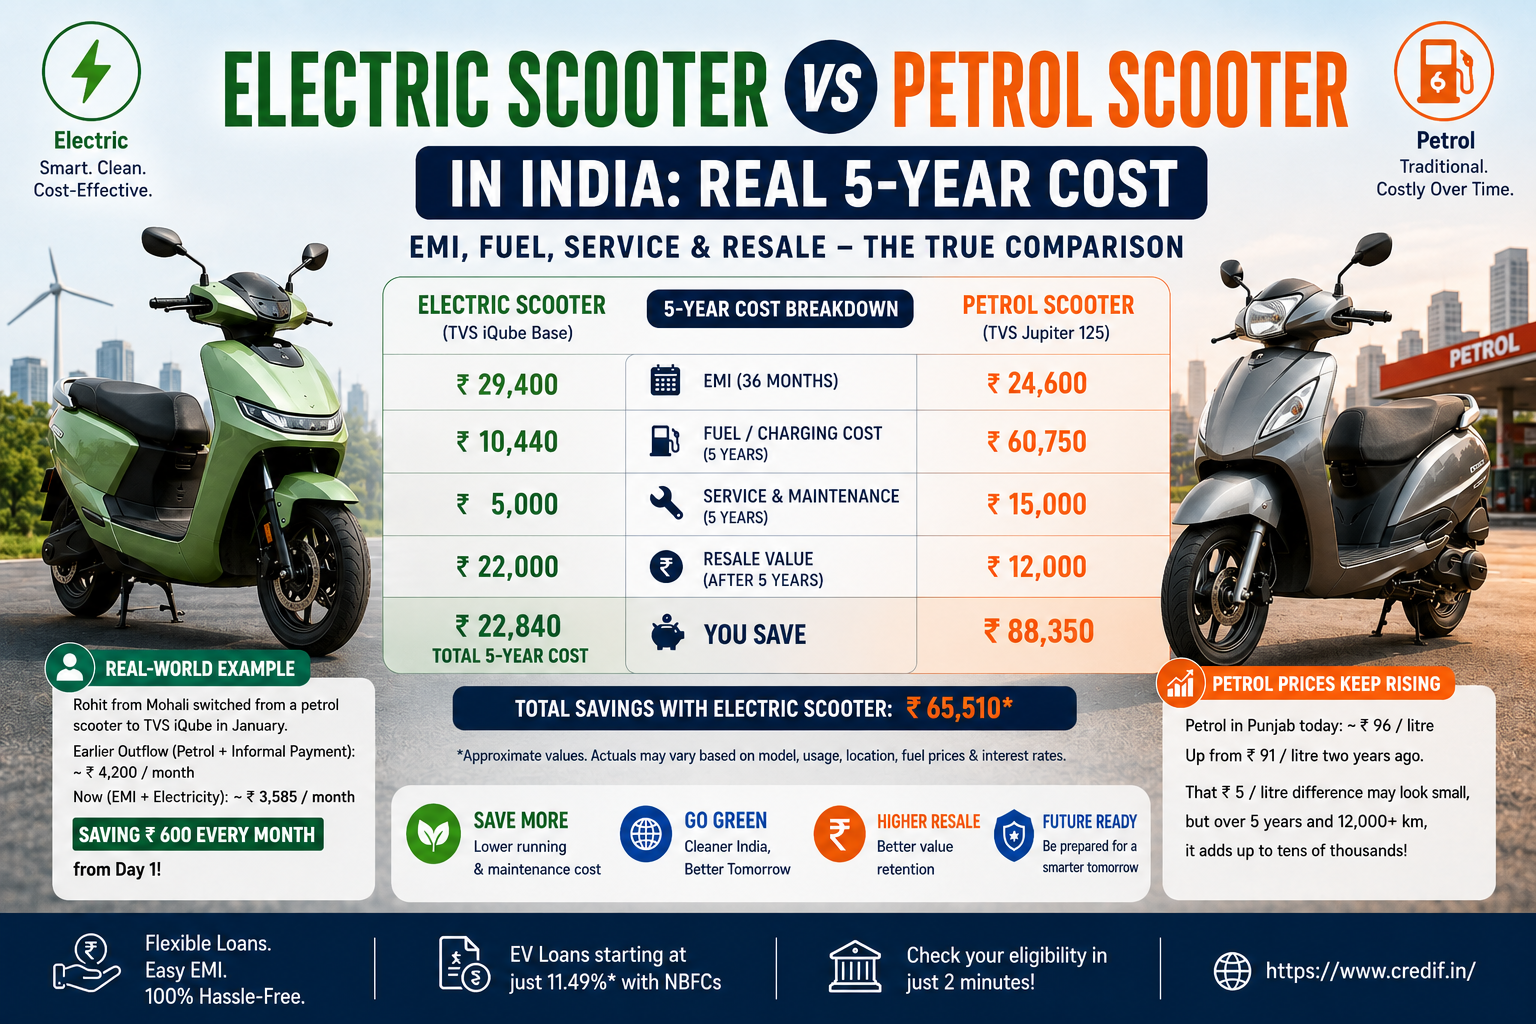
A 36-month tenure on a 1.5 lakh loan works out to about 5,200 rupees a month. Compare that to the 1,400 rupees a month petrol bill my uncle was paying, plus 800 to 1,000 in maintenance and oil changes. EV running cost is roughly 300 rupees a month in electricity for that same usage. So the EMI eats up most of the savings in year one, but by year two onwards you're genuinely ahead.
If you keep the scooter for 5+ years, the lifetime savings versus a petrol equivalent are substantial. If you sell it after 2 years, the math is roughly break-even because EV resale is still weaker than petrol. We've done the full five-year electric vs petrol scooter cost separately.
Who should actually finance an EV scooter?
A few clean cases:
The case is weaker if you live in a flat with no charging access, or you ride less than 15 km a day, or you live in a state where electricity costs above 8 rupees per unit at home.
Subsidies you can claim
Central support is smaller than it used to be: PM E-DRIVE gives Rs 2,500 per kWh, capped at Rs 5,000 per scooter, and has been extended to March 2028 subject to funds. State subsidies still apply heavily though.
- Delhi: Up to Rs 30,000 + road tax exemption + registration fee waiver
- Maharashtra: Up to Rs 10,000 + road tax waiver
- Gujarat: Road tax concession (the earlier cash subsidy has ended)
- Telangana: Road tax + registration fee waiver (no direct subsidy)
- Punjab: Registration fee waiver + road tax exemption
- Haryana: Road tax exemption
State policies change often, so check your state transport department's current notification before you buy. Our state-wise EV subsidy list covers three-wheelers and cars too.
Most subsidies are auto-applied at the dealer level now, but verify the discount is reflected on your invoice before signing. I've seen cases where the dealer charged the full price and pocketed the subsidy. Insist on seeing it broken out on paper.
Documents you'll need
- PAN, Aadhaar
- 3 latest salary slips
- 6 months bank statement of salary account
- Address proof
- A photo
- PAN, Aadhaar
- 2 years ITR with computation
- 12 months bank statement of business account
- GST cert or shop license
- Address proof
- PAN, Aadhaar
- Partner ID screenshot from the platform
- 6 months bank statement (the account where payouts come in)
- Address proof
- A guarantor sometimes, depends on platform tenure
NBFCs are way more flexible on the gig worker bucket than banks. Banks usually want salaried documentation. NBFCs read the partner payout pattern and approve on that. The full EV loan documents checklist goes profile by profile.
A delivery rider's loan from Mohali
Aman, 24, rides for Zomato in Mohali, mostly Sector 70 and Phase 7 areas. Has been at it for 14 months. His Activa was eating 280 rupees a day in petrol because Zomato delivery means short trips with constant stop-start (worst case for fuel efficiency).
Looked at the Ola S1 X (cheapest in their lineup). On-road around 1.05 lakh in Punjab. He had 20k saved. Needed 85k loan.
Two private banks rejected him because he didn't have an ITR or salary slip. The NBFC (Credifin) looked at his bank statement, saw consistent Zomato payouts of 28 to 35k monthly for over a year, approved 85k at 16 percent over 30 months. EMI 3,456. Disbursal in 5 working days.
His daily numbers now: charges at home overnight (about 20 rupees of electricity for a full charge), runs 90 to 110 km per day on one charge. Saving roughly 220 rupees a day in fuel vs his old Activa. Net cash flow improvement: about 6,600 a month. EMI is 3,456. He's pocketing about 3,100 extra a month plus building ownership in a vehicle that's actually his.
Said the only headache so far was finding a charging point near his pickup area for top-ups on long days. He worked it out by leaving the Ola at a friend's PG mid-shift for 90 minutes.
What can trip up an EV scooter loan application
A few things I've seen repeatedly:
No or weak CIBIL. First job, first credit account, no history yet. NBFCs accept this with a guarantor, banks usually don't. More on the CIBIL score you need for an EV loan.
Recent loan defaults. Even a 5,000 rupee BNPL miss can flag you. Clear it, wait, then apply.
Job tenure under 6 months. Banks want at least 6 months at current employer. Gig workers' "tenure" is the platform partner ID date.
Address mismatch with Aadhaar. Update Aadhaar first.
Multiple loan applications in 30 days. Hard credit pulls stack up. Pick one bank, one NBFC. Run them parallel.
Where Credifin sits in this market
Credifin does EV two-wheeler loans across 14 states, including Punjab, Haryana and Delhi NCR. The assessment is built around what you actually earn, including gig worker payouts, shopkeeper bank deposits, and salaried profiles with informal salary structures.
Your rate depends on your profile, and it's shared in writing before you sign. The Jalandhar branch handles RC, hypothecation, and insurance routing in one place so you're not chasing three desks. Online application takes 15 minutes, decision in 3 to 7 days for clean profiles.
We finance petrol two-wheelers too, but EVs are where we specialise.
Wrapping up
An EV scooter loan in 2026 is genuinely easier than it was even two years ago. Rate range of 12 to 18 percent across most lender types. EMI on a typical 1.5 lakh on-road model is around 5,200 a month for 3 years. Subsidies still meaningful in most states.
The bigger question is whether the EV scooter itself fits your usage. If you ride 30+ km a day, deliver for a platform, or live in a state with heavy state subsidy plus rooftop solar at home, the math is obviously in your favour. If you ride 8 km on weekends only, a petrol Activa is probably still the right pick.
Loan is the easy part. Pick the right vehicle first.
Visit us in Jalandhar
Credifin Limited
87, Radio Colony, New Jawahar Nagar, Mahavir Nagar
Jalandhar, Punjab 144001
079651-74500 | info@credif.in
Find your nearest branch →
FAQs
What's the minimum downpayment for an EV scooter loan?
5 to 10 percent at NBFCs if your profile is strong. Banks usually want 10 to 15 percent. Some captive financing options go to zero downpayment but the interest rate compensates. See how much down payment an EV really needs.
EV scooter loan vs petrol scooter loan, any rate difference?
Used to be a 1 to 2 percent gap, mostly closed now. Some banks even offer green vehicle discounts of 25 to 50 basis points for EVs.
Can gig workers (Zomato, Swiggy) get an EV scooter loan?
Yes, through NBFCs that accept platform payout statements. Most banks won't.
Are there tax benefits for EV scooter loans?
Section 80EEB lets you deduct up to Rs 1.5 lakh a year in interest paid on an EV loan from your taxable income, for loans sanctioned between April 2019 and March 2023, under the old tax regime, until the loan is repaid. The scheme hasn't been extended for new loans yet as of 2026, but check the latest budget update. Our Section 80EEB guide covers who still qualifies.
Do lenders accept PM E-DRIVE or state subsidies as downpayment?
No. Subsidy is deducted from the on-road price first, and you finance the post-subsidy price. So a 1.5 lakh scooter in Delhi becomes effectively about 1.2 lakh and you finance against that.
What's the EMI for a 1.5 lakh EV scooter loan?
At 15 percent, roughly 7,273 for 24 months, 5,200 for 36 months, 4,175 for 48 months.
Can I get 100 percent financing on an EV scooter?
Some NBFCs do this for repeat customers or strong profiles. Banks usually require at least 5 to 10 percent down.
How long is approval?
3 to 7 working days for NBFCs with clean documents. Banks take 7 to 14.
Can I prepay the loan?
Yes, most lenders allow this after 6 months of regular EMIs. Some charge 2 to 5 percent prepayment fee.
Ready to apply?
Switching from petrol to electric? Apply for an EV scooter loan with Credifin online or visit the Mahavir Nagar branch in Jalandhar. We finance every major EV scooter brand, including gig worker profiles that banks reject. Decision in 3 to 7 days.
Check your eligibility →Credifin Limited is an RBI-registered NBFC, CRISIL BBB-/Stable. Loans at the sole discretion of the company. Rates, prices and subsidies mentioned are indicative and can change; they are not an offer.
This might catch your interest